Commercial building insurance is insurance for the physical structure of premises used for business, including permanent fixtures and installations. It may respond to damage from insured events, depending on the policy wording, exclusions and conditions.
For owners and managing agents, commercial real estate insurance brings buildings, rental income and ownership-related liability into the wider assessment of property exposures.
If you own the freehold or long leasehold of a commercial property, commercial building insurance is likely to be one of the most important policies you will ever buy. It protects the physical structure of the premises against fire, flood, storm, escape of water, impact, vandalism and a long list of other insured perils: and, in most cases, it is a contractual requirement under your mortgage or lease.
This guide explains exactly what commercial building insurance is, what it covers and excludes in the UK market, how premiums are calculated, and how to choose a policy that actually pays out when you need it to. You can also read more about how we arrange this cover on our commercial property insurance page.
Who This Guide Is For
- Freeholders
- Landlords
- Property owners
- Investors
- Managing agents
What Is Commercial Building Insurance?
Commercial building insurance is a property policy that covers the physical fabric of a non-residential building: the walls, roof, floors, foundations, fixtures and permanent installations such as wiring, plumbing and lifts. It is designed for owners of commercial premises rather than tenants; tenants usually buy contents and business interruption cover instead, and rely on the landlord to insure the structure.
In the UK, a typical commercial buildings policy is written on an "all risks" basis, meaning the insurer covers any sudden and accidental damage unless it is specifically excluded. Older or higher-risk properties are sometimes written on a "named perils" basis, which only covers the perils listed in the policy schedule (fire, lightning, explosion, escape of water, storm, theft, malicious damage and so on). All risks cover is broader and is generally what most UK owners should aim for.
Commercial building insurance is distinct from contents insurance (which covers stock, fixtures, fittings and equipment) and from liability insurance (which covers your legal liability to third parties). Most commercial property packages combine buildings, contents, business interruption and property owners' liability into a single schedule, but the buildings section is usually the largest single line of cover.
What Does Commercial Building Insurance Cover?
The exact wording varies between insurers, but a modern UK commercial buildings policy will usually include the following sections of cover.
Damage to the structure
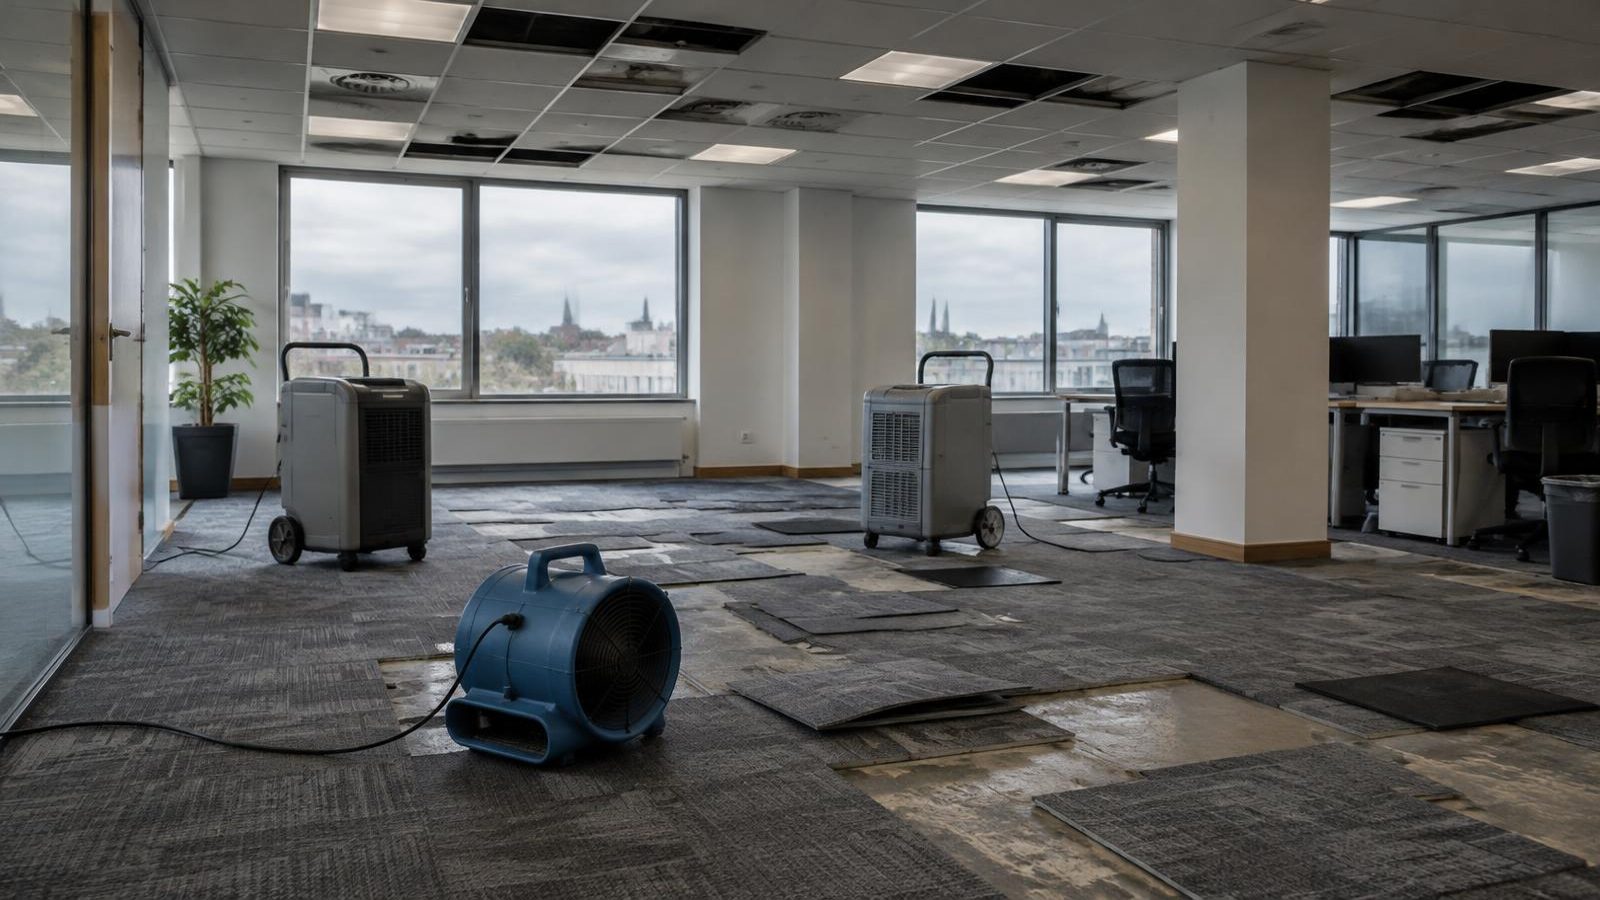
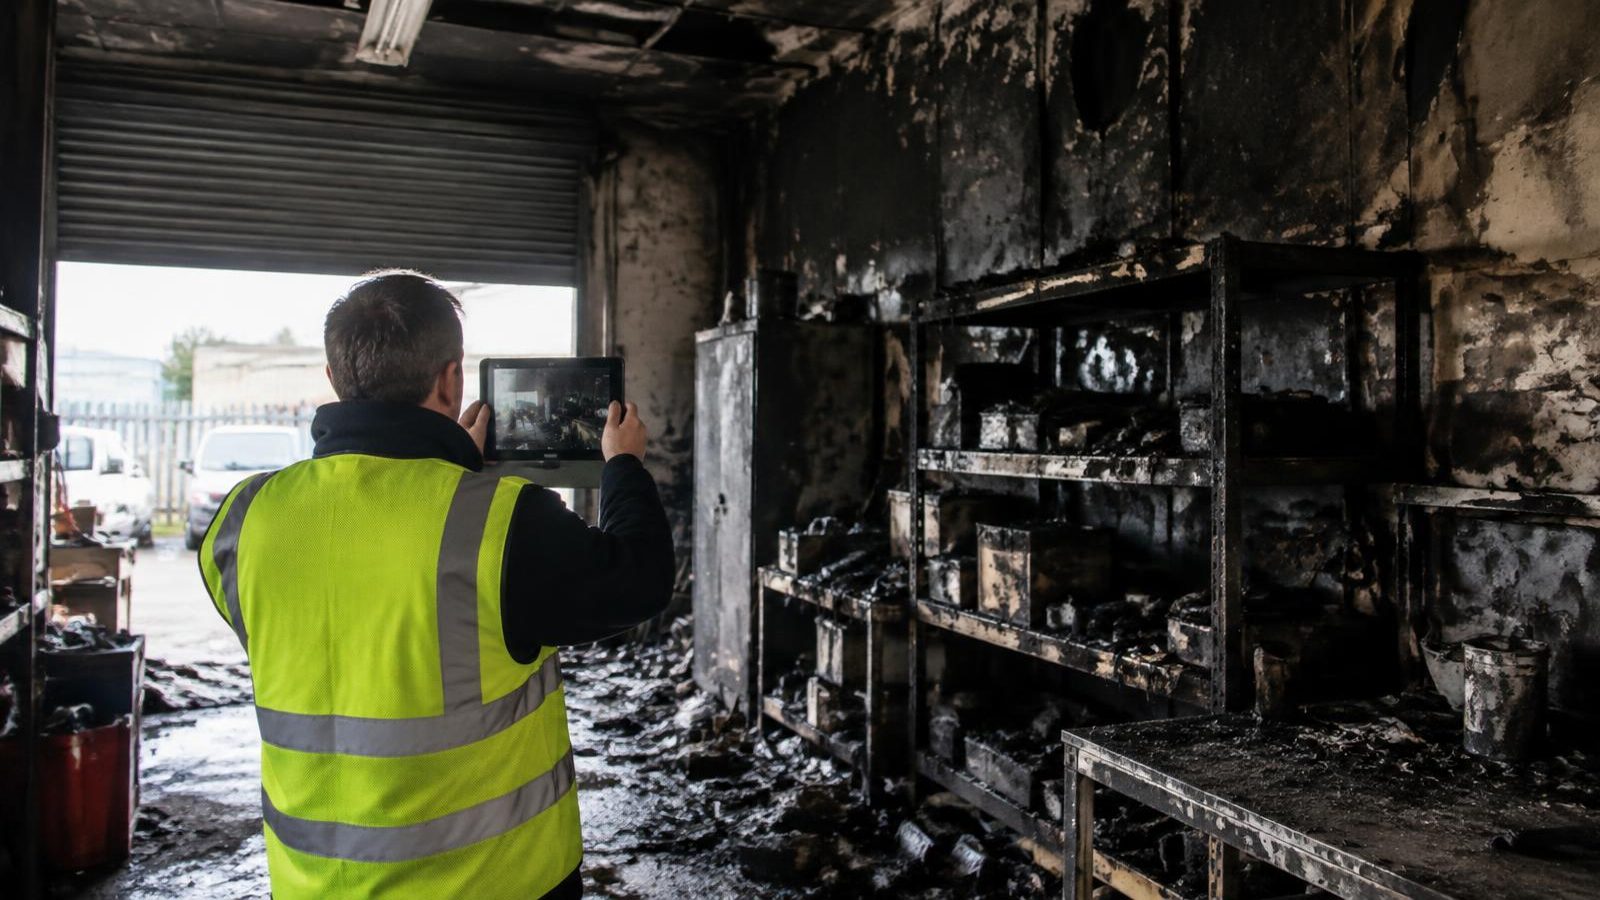
Cover for the building itself against fire, lightning, explosion, aircraft impact, storm, flood, escape of water, theft involving forcible entry, malicious damage, riot, civil commotion, impact by vehicles or animals and: on an all risks wording: any other accidental damage not specifically excluded. Reinstatement is typically on a "new for old" basis, subject to the sum insured being adequate.
Subsidence, heave and landslip
Most UK commercial buildings policies include subsidence cover as standard, but it is often subject to a higher excess (typically £1,000 to £2,500) and to a survey if the property has a history of movement. Locations with shrinkable clay subsoils, mature trees, mining or coastal erosion can attract additional terms.
Property owners' liability
This section covers your legal liability as the property owner for injury to third parties or damage to their property arising from the premises: for example, a visitor injured by a falling sign or a contractor harmed by a defective stair. Limits of £2 million to £10 million are common, with £5 million being a sensible default for most properties. Standalone terrorism cover for higher-risk locations is available through a range of insurers, subject to their terms.
Loss of rent and alternative accommodation
If an insured event makes the premises uninhabitable, your policy can pay the rent you lose while the property is being reinstated. The indemnity period (usually 12, 24 or 36 months) should reflect realistic reinstatement timescales for your property: a complex listed building or a large industrial unit can easily take more than 12 months to rebuild.
Glass, signs and external structures
Fixed glass, shopfronts, illuminated signs, walls, gates, fences and external infrastructure are usually included up to a sub-limit. If you have significant signage, expensive glazing or extensive grounds, check the sub-limits carefully or arrange specific cover.
Loss of Rent Cover Explained
Loss of rent cover may address rental income lost when insured damage prevents the premises from being used. Depending on the wording, events such as fire, storm, flood or escape of water may trigger it when they are insured under the policy.
The indemnity period is the time for which eligible rent loss may be paid. Consider likely reinstatement, planning and tenant return needs, alongside the sum insured and the policy conditions.
What May Not Be Covered
- Routine vacancy between tenants without insured damage.
- Rent arrears or tenant default, unless separately insured.
- Loss caused by an excluded event or failure to meet policy conditions.
- Income outside the agreed indemnity period or beyond the sum insured.
Read our loss of rent insurance guide for further detail, or discuss the property’s rental exposure with commercial real estate insurance specialists.
What Is Typically Excluded?
No commercial buildings policy covers everything. Standard UK exclusions include wear and tear, gradual deterioration, faulty design or workmanship, war and nuclear risks, pollution and contamination (other than as a result of an insured peril), unoccupancy beyond a stated period (often 30 to 60 days) and damage caused by pests or vermin.
Flood, terrorism and cyber are sometimes included and sometimes excluded depending on the insurer and the property's risk profile. Standalone terrorism cover (available through specialist insurers) is strongly recommended for properties in central London, transport hubs or close to recognisable targets. Cyber cover is rarely relevant to a buildings policy, but escape of water from connected building management systems is increasingly being scrutinised by underwriters.
Who Needs Commercial Building Insurance?
Anyone with a financial interest in a commercial property structure may want to consider buildings cover: though the decision will depend on factors such as lender requirements, lease obligations and the owner's own appetite for carrying the risk. In practice that means freeholders, long leaseholders, commercial landlords, owner-occupiers, property investors, property management companies and trustees of premises owned by pension schemes, charities or family trusts.
Tenants on a full repairing and insuring (FRI) lease do not buy buildings cover directly, but they are usually obliged to reimburse the landlord's premium as part of the rent. Tenants should still check that the policy in place is appropriate, that the sum insured is adequate, and that their own contents and business interruption cover dovetails with the landlord's buildings policy.
If You Own Commercial Property
Review the structure, rental income and property owners’ liability alongside the lease and risk details. Explore commercial property insurance for owners and investors for advice on arranging an appropriate programme.
If You Let Residential Units
Residential letting may need a different policy structure from commercial premises. Explore portfolio landlord insurance for residential units; for mixed-use buildings, discuss the business and residential parts with commercial real estate insurance advisers.
How Much Does It Cost in the UK?
Premiums depend on a range of factors. The most important is the buildings sum insured (the cost of rebuilding the property from the ground up, including professional fees, demolition and debris removal, and VAT where applicable). Insurers also look at construction (modern brick and steel is rated more favourably than timber-framed or composite-clad buildings), occupancy (a low-risk office is cheaper than a hot-works engineering unit), location, claims history, fire and security protections, and the trade carried out at the premises.
Underinsurance is one of the biggest causes of unhappy claims outcomes in the UK commercial property market, and industry research by the Association of British Insurers regularly highlights how widespread the problem is. Rebuild costs have risen sharply in recent years and many sums insured set five or ten years ago may no longer reflect current costs. A RICS reinstatement cost assessment, or "Day One" uplift on the declared sum insured, is one of the simplest ways to protect against this. Day One uplifts in the UK market can often be set at up to 50% of the buildings declared value, which provides a useful cushion against rebuild cost inflation between renewal and the date of any reinstatement. Our team can arrange a valuation as part of broader commercial property cover.
Read what affects commercial property insurance costs for the rating factors insurers assess. Independent commercial insurance brokers can help review the cover and risk details.
Use official GOV.UK flood information to check location-specific flood exposure.
How to Choose the Right Policy
Three things matter more than the headline premium: the adequacy of the sum insured, the breadth of the wording and the strength of the insurer behind it. A cheap policy with a low sum insured, narrow perils and a weak balance sheet may cost you many multiples of the headline saving the first time you need to make a serious claim.
- Insist on an up-to-date reinstatement cost assessment, ideally by a RICS-qualified surveyor.
- Read the wording: particularly the unoccupancy conditions, the subsidence excess, the indemnity period for loss of rent and any warranties relating to fire alarms, sprinklers or intruder alarms.
- Check the insurer's claims service and financial strength rating: A-rated UK insurers are the sensible benchmark.
- Make sure your buildings, contents and business interruption sums insured are consistent with each other and reviewed at every renewal.
- Disclose all material facts: including past claims, subsidence history, any non-standard construction and any commercial use that is not obvious from the address.
Why Work With a Specialist Broker
Direct insurers and price-comparison sites struggle with the nuance of commercial property. A specialist broker compares wordings rather than just prices, advises on sums insured and indemnity periods, handles the disclosure exercise properly, and represents you when something goes wrong. Taurus Risk arranges commercial property insurance for landlords, investors and owner-occupiers across the UK, and can usually access wordings and rates not available direct.
Frequently Asked Questions
Is commercial building insurance a legal requirement in the UK?
Commercial building insurance is not a legal requirement in the same way that employers' liability insurance is, but it is almost always a contractual requirement under a commercial mortgage or lease. Lenders insist on it to protect their security and landlords insist on it to protect their asset.
What is the difference between commercial building insurance and commercial property insurance?
"Commercial building insurance" refers specifically to cover for the physical structure of a non-residential property. "Commercial property insurance" is a broader term that usually combines buildings, contents, stock, business interruption and property owners' liability into one package. Most UK insurers sell them on the same policy schedule.
Who pays for commercial building insurance: the landlord or the tenant?
The landlord almost always arranges the buildings policy. Under a standard full repairing and insuring (FRI) lease, the cost is then recharged to the tenant as part of the rent or service charge. The lease should set out clearly who arranges cover, what perils must be insured against and how the premium is apportioned.
How do I work out the buildings sum insured?
The sum insured should reflect the full reinstatement cost of the building: what it would cost to rebuild it from the ground up, including professional fees, debris removal, demolition, planning costs and VAT where applicable. It is not the market value or the purchase price. A RICS reinstatement cost assessment is generally a reliable way to set it.
Does commercial building insurance cover flood damage?
Most policies include flood as a standard insured peril, but properties in high flood-risk postcodes may face higher premiums, larger excesses or specific flood exclusions. Flood Re does not apply to commercial property in the UK, so flood-prone commercial buildings need to be placed in the specialist market.
What happens if my property is empty between tenants?
Cover may be restricted when a property is empty beyond the unoccupancy period stated in its policy wording. Confirm the insured perils and the insurer’s inspection, security and water-system conditions. Tell your broker as soon as a property becomes unoccupied to avoid an unintended gap in cover.
How quickly will an insurer pay a claim?
Smaller claims (such as escape of water or storm damage to a roof) are often settled within weeks. Larger losses involving total loss, business interruption or subsidence can take many months and usually involve a loss adjuster. A broker's role at this stage is to make sure your interests are properly represented and the settlement reflects the cover you have paid for.
What is loss of rent cover?
Loss of rent cover may reimburse rental income lost when an insured event makes the property unusable, depending on the policy. Check the insured events, indemnity period, sum insured, conditions and exclusions; it is not generally protection against routine vacancy or unpaid rent.