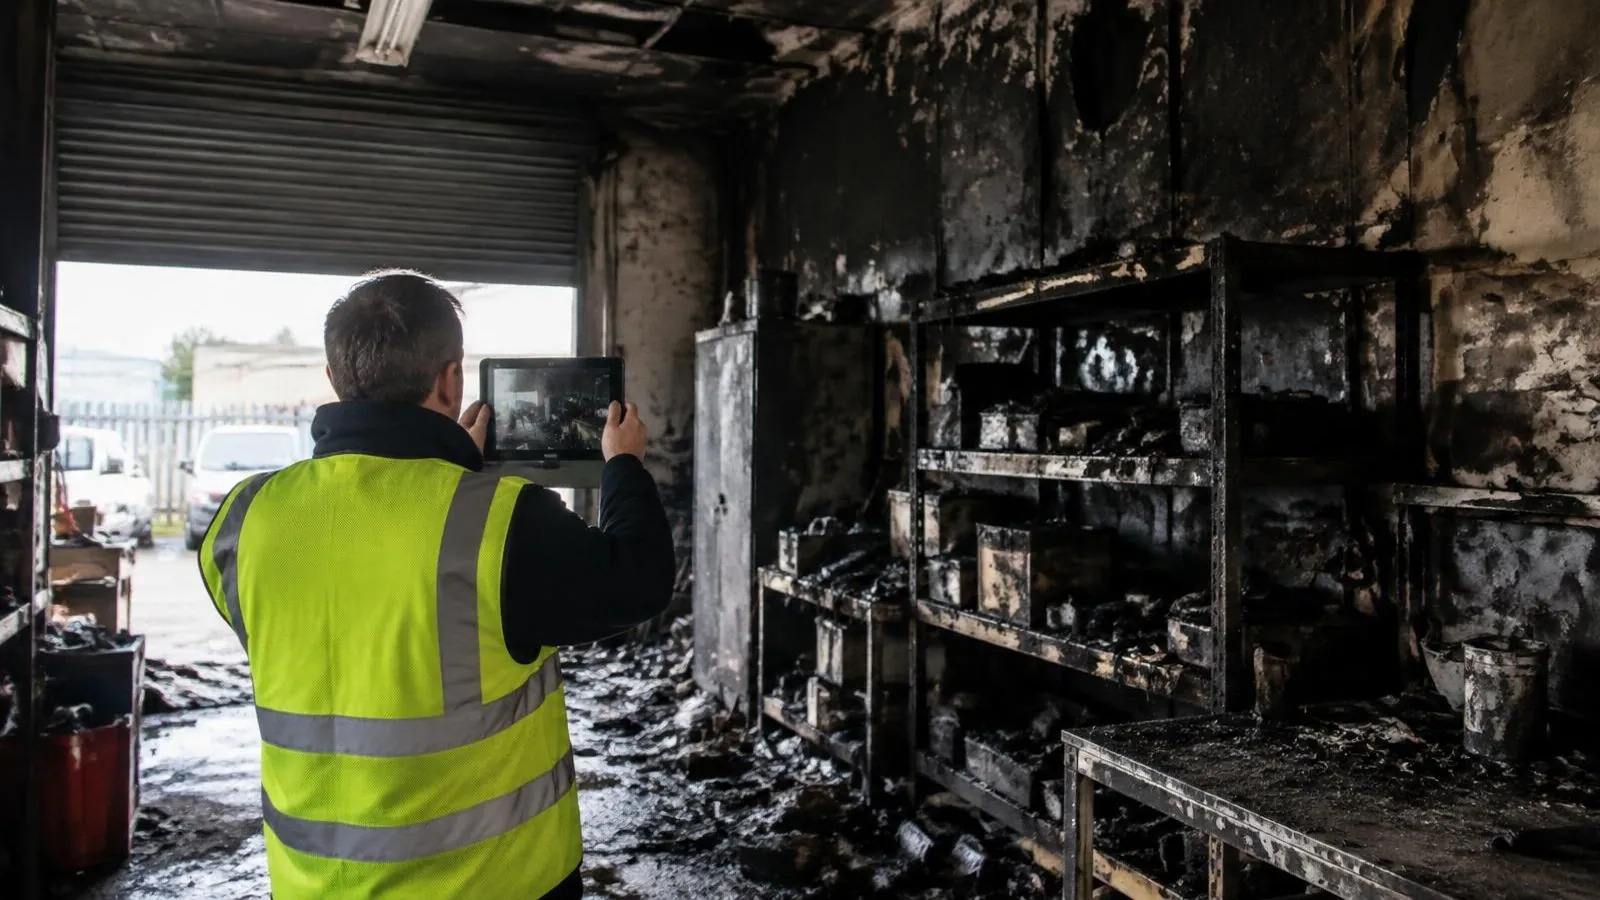
When something goes wrong, make people and premises safe, take reasonable steps to stop the loss getting worse, record what has happened, and notify your broker or insurer as soon as you can. Do not admit liability to anyone, and do not dispose of damaged items or start permanent repairs until the insurer agrees. Insurers will then check five things: that the event is covered, that policy conditions were met, that the risk was presented fairly when cover was bought, that the amount claimed is properly evidenced, and that you acted to limit the loss.
Most commercial claims are paid without dispute. Where claims run into difficulty, it is usually because of late notification, missing evidence, a condition that was not met, or information that was wrong when the policy was arranged. Knowing what insurers look for helps you avoid all four.
Related cover: Commercial Combined, Business Interruption
The First 24 Hours
- 01
Make it safe
Deal with immediate danger, call the emergency services where needed and get people out of harm's way. - 02
Prevent further loss
Isolate water, secure the premises, board up broken windows and move undamaged stock or equipment out of harm's way. Reasonable emergency costs are often recoverable, so keep receipts. - 03
Report crime
For theft, burglary or malicious damage, report it to the police and note the crime reference number. - 04
Record everything
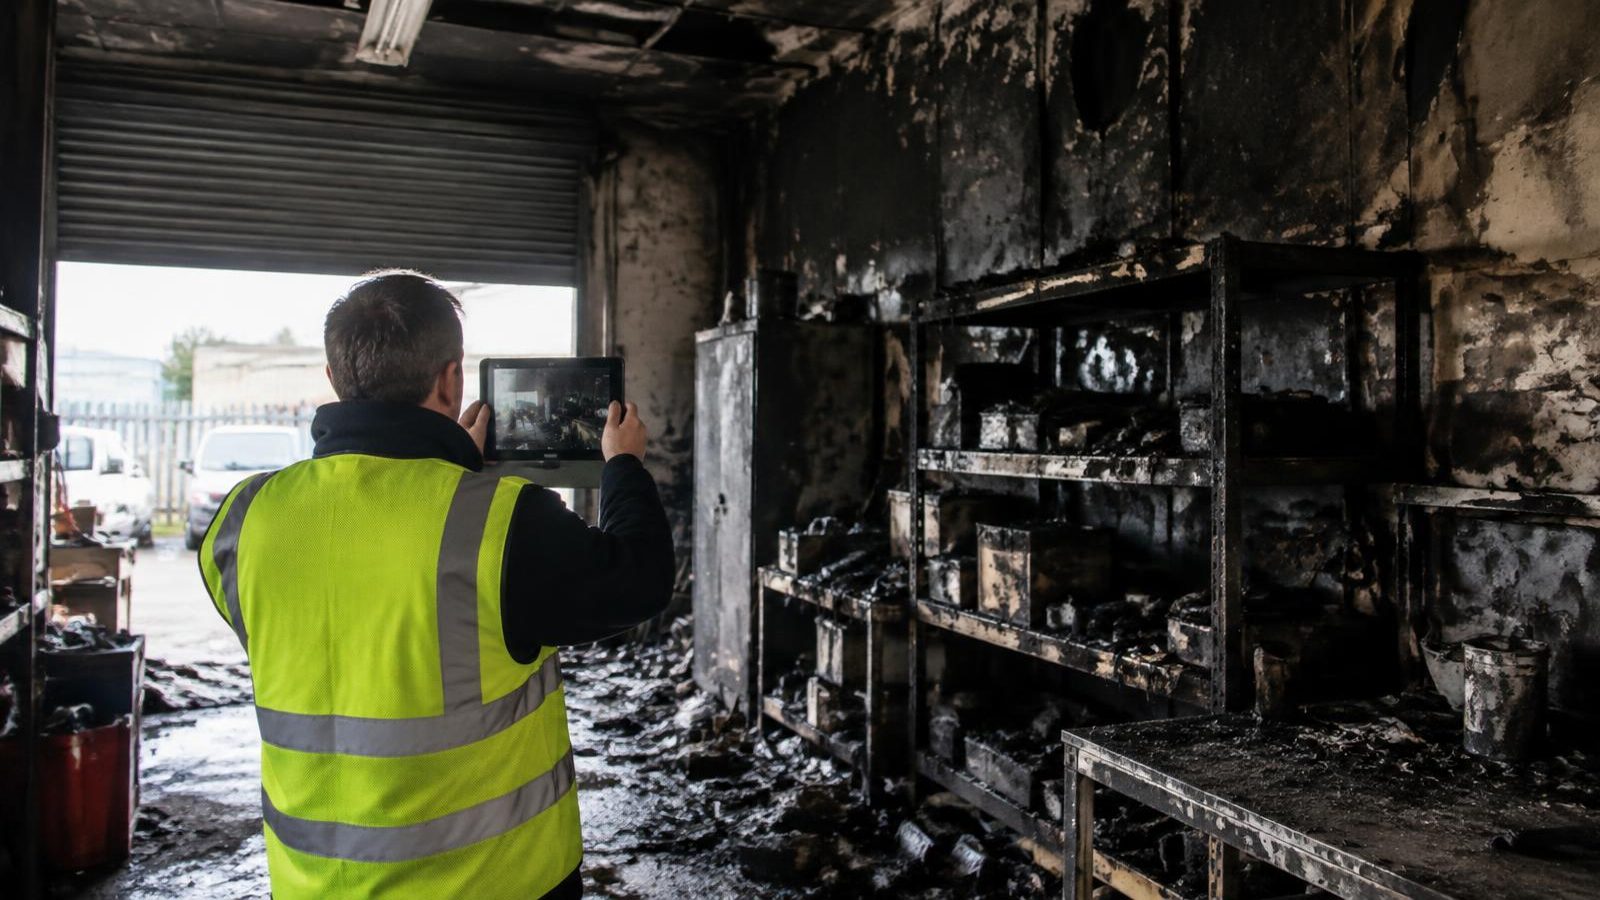
Photograph and video the damage before anything is moved, note times and what you saw, and keep damaged items unless the insurer agrees otherwise. - 05
Notify your broker or insurer
Give the policy number, what happened and when, and an initial idea of the scale. You do not need every figure to notify. - 06
Say nothing about fault
If a third party is involved, take their details but do not admit liability or offer payment.
Injuries at work
Notifying Your Insurer
Most commercial policies require notification as soon as reasonably practicable, and some set specific time limits for certain types of claim. Depending on the wording, late notification can give the insurer grounds to reduce or decline a claim, particularly where the delay has made the loss worse or harder to investigate.
Two types of policy need particular care:
- Claims-made policies, such as professional indemnity and directors' and officers' insurance, generally respond to claims first made, or circumstances first notified, during the policy period. If you become aware of something that might lead to a claim, such as a complaint or an error, notify it before the policy expires even if no formal claim has been made. Our professional indemnity insurance guide explains how this works.
- Liability policies. Pass any letter of claim, solicitor's letter or court document to your insurer the same day. Formal claims carry short response deadlines, and the insurer will normally take over handling of the claim.
What Insurers Look For
Once a claim is notified, the insurer or its loss adjuster will work through five questions.
1. Is the event covered? Was there an insured event, at an insured location, within the period of insurance, not caught by an exclusion? For example, wear and tear, gradual deterioration and poor maintenance are typically excluded from property cover, while a sudden escape of water is typically insured. Our guides to office insurance exclusions and portfolio landlord exclusions show common examples.
2. Were the conditions met? Insurers will check relevant conditions such as alarm requirements, unoccupied property inspections, electrical testing or security standards. Under the Insurance Act 2015, an insurer generally cannot rely on breach of a term aimed at a particular kind of loss to decline a claim if the breach could not have increased the risk of the loss that actually occurred. Even so, complying with conditions remains the safest course.
3. Was the risk fairly presented? The insurer may compare what it was told when cover was arranged with what it finds. If material information was missing or wrong, the remedies under the Insurance Act 2015 are proportionate to what the insurer would have done had it known: the claim may be paid on different terms, reduced in proportion, or the policy avoided where the insurer would not have offered cover at all or the failure was deliberate or reckless.
4. Is the amount properly evidenced? The insurer needs to see invoices, asset registers, repair estimates and, for business interruption, accounts and management figures. Sums insured are also checked: if they are too low, average may reduce the payment.
5. Did you mitigate the loss? Insurers expect reasonable steps to stop the loss getting worse. Delays that allow damage to spread can affect what is paid for the additional damage.
Loss Adjusters, Loss Assessors and Your Broker
For larger or more complex claims, the insurer will usually appoint a loss adjuster. Adjusters investigate the cause, check the cover and quantify the loss, and they report to the insurer. They do not act for you, but a good adjuster will explain the process and what they need.
A loss assessor is different. An assessor is appointed by the policyholder to prepare and negotiate the claim, usually for a fee based on a percentage of the settlement.
Your broker sits on your side of the table. A good broker will help present the claim, chase progress, challenge decisions that do not reflect the wording and escalate where needed. Claims support is part of what you should expect from a commercial broker, and our guide to choosing a commercial insurance broker covers what to ask.
Independent Commercial Insurance Advice
Taurus Risk is an independent, FCA-regulated specialist insurance broker. We aim to explain business claim notification, evidence and settlement in plain terms and to support clients through renewals and claims.
- Access to UK insurers that write commercial business risks
- Policy wordings explained in plain terms
- Support from a named broker
A response within 24 working hours, no obligation
Business Interruption Claims
Business interruption claims compare what the business actually earned during the indemnity period with what it would have earned without the damage. Expect to provide:
- Recent management accounts and statutory accounts
- Budgets and forecasts prepared before the loss
- Evidence of increased costs, such as temporary premises, overtime or equipment hire
- Monthly figures through the recovery period
Involve your accountant early. Some policies include cover for reasonable claim preparation costs, such as accountants' fees, so check your wording. Our guide to business interruption insurance for offices explains how cover is calculated.
How Long Claims Take
Straightforward claims can be settled in days or weeks. Large property, business interruption and liability claims can take months, and liability claims can take longer where court proceedings are involved.
For policies entered into on or after 4 May 2017, the Insurance Act 2015, as amended by the Enterprise Act 2016, implies a term that insurers must pay sums due within a reasonable time. What is reasonable depends on the size and complexity of the claim. FCA rules also require insurers to handle claims promptly and fairly.
On larger claims, insurers can make interim payments while the claim is still being finalised, which can be important for cash flow. Ask about them early.
If You Disagree With a Decision
If a claim is declined or reduced, ask for the reasons in writing, with reference to the specific policy wording. Then:
- Ask your broker to review the decision and challenge it where the wording supports you.
- Use the insurer's formal complaints procedure.
- If you are an eligible smaller business, you may be able to refer an unresolved complaint to the Financial Ombudsman Service, which is free to use. Eligibility depends on factors such as headcount, turnover and balance sheet.
- Larger businesses may need to rely on mediation, arbitration or the courts, depending on the policy terms.
Our article on what to do when a pub insurance claim is denied works through how declined claims are typically handled.
How to Make Future Claims Easier
- Keep sums insured accurate and review rebuild costs regularly
- Maintain an asset register, and keep copies of key records off site or in the cloud
- Keep maintenance, inspection and testing records
- Tell your broker about changes to the business or premises when they happen
- Know your policy conditions, especially security and unoccupancy requirements
- Have a business continuity plan, so everyone knows who does what after an incident
Our guide to business risk management explains how to plan for the events most likely to interrupt your business, and our guide to comparing commercial insurance quotes shows how to check cover before you need it.
Frequently Asked Questions
What should I do first after a business insurance loss?
Make people and premises safe, take reasonable steps to prevent further damage, report any crime to the police, photograph the damage, and notify your broker or insurer as soon as possible. Do not admit liability or dispose of damaged items without the insurer's agreement.
How soon do I need to notify my insurer of a claim?
Most commercial policies require notification as soon as reasonably practicable, and some set specific time limits. For claims-made policies such as professional indemnity, circumstances that might lead to a claim should be notified before the policy expires.
Should I start repairs before the loss adjuster visits?
Carry out emergency repairs needed to prevent further damage and keep receipts and photographs. Agree permanent repairs with the insurer or loss adjuster before starting them, and keep damaged items unless told otherwise.
What is the difference between a loss adjuster and a loss assessor?
A loss adjuster is appointed by the insurer to investigate and quantify the claim. A loss assessor is appointed by the policyholder to prepare and negotiate the claim on their behalf, usually for a percentage fee.
Why do insurers decline business insurance claims?
Common reasons include the event not being covered, an exclusion applying, a policy condition not being met, late notification, inaccurate information given when cover was arranged, or insufficient evidence of the loss.
How long does a business insurance claim take?
Simple claims can settle in days or weeks, while large property, business interruption and liability claims can take months or longer. Insurers must pay sums due within a reasonable time, and interim payments may be available on larger claims.
Can a business complain to the Financial Ombudsman about a declined claim?
Eligible smaller businesses may be able to refer an unresolved complaint to the Financial Ombudsman Service after using the insurer's complaints procedure. Eligibility depends on factors such as headcount, turnover and balance sheet.