For most office businesses, business interruption insurance is worth having. Buildings and contents cover pays to repair or replace what is damaged, but it does not replace lost income or pay the salaries, rent and loan repayments that continue while the business recovers. Business interruption cover is designed to fill that gap. It is worth less to a business that could switch to remote working immediately with little loss of income, and more to one that relies on its premises, equipment or client-facing space.
Our existing guides cover what office insurance includes and common office insurance exclusions. This guide looks at income protection specifically: what business interruption insurance does, when it earns its premium, and how to set it up so it pays what you expect.
Related cover: Business Interruption
What Business Interruption Insurance Covers
Business interruption insurance, sometimes called loss of profits cover, pays for the financial impact of an interruption caused by insured damage. For an office business, cover is usually built around:
- Loss of gross profit or revenue: the shortfall in income compared with what the business would have earned, less any costs that stop as a result.
- Increased cost of working: reasonable extra costs to keep trading, such as temporary offices, equipment hire, IT recovery or overtime.
- Continuing costs: salaries, rent, finance and other costs that carry on while income is reduced, which are generally protected through the gross profit calculation.
- The indemnity period: the maximum period over which the policy pays, starting from the date of the damage.
Many policies also offer extensions for interruptions caused by damage elsewhere, such as:
- Denial of access, where damage nearby prevents you using your premises
- Failure of public utilities, such as electricity or telecommunications, usually subject to conditions
- Damage at the premises of key suppliers or customers
The Damage Trigger
Most business interruption cover only applies when the interruption follows physical loss or damage insured under the property section of the policy. This requirement, often called the material damage proviso, means that if the cause is not an insured peril, or the property cover does not respond, the business interruption cover usually will not respond either.
That is why business interruption is best arranged alongside your property cover, and why accurate sums insured on the property side matter for income protection too.
Interruptions with no physical damage, such as an economic downturn, the loss of a major client or a dispute with a landlord, are generally outside standard cover. Disease-related closures depend entirely on the wording: the FCA's business interruption test case, decided by the Supreme Court in January 2021, showed how much the outcome can turn on specific policy language.
Cyber and IT outages
When It Is Worth It, and When It Is Worth Less
- Businesses that rely on their premises to trade, such as client-facing practices, studios or firms with on-site servers and records
- Businesses with high fixed costs, such as long leases, large payrolls or significant borrowing
- Firms that would lose clients to competitors during a long disruption
- Businesses in multi-occupied buildings, where damage elsewhere in the building could close access
- Businesses whose lease requires rent to continue after damage
- Fully remote businesses with minimal physical assets
- Businesses that could relocate within days with little loss of income
- Firms with large cash reserves and low fixed costs
- Businesses whose income would not fall even if the office closed
Many commercial leases include a rent suspension clause that stops rent being payable while the premises are unusable because of damage by an insured risk, but terms vary between leases and the suspension may only last for a set period. It is worth checking your lease: if rent continues, it is a cost your business interruption cover needs to fund.
Hybrid working can also make dependence on the office easy to underestimate. Staff may be able to work from home for a few days, but client meetings, paper records, specialist equipment and the office as a base for the team are often harder to replace. Our guide to office insurance for hybrid and remote businesses looks at how cover should reflect the way you work.
What a Claim Might Look Like
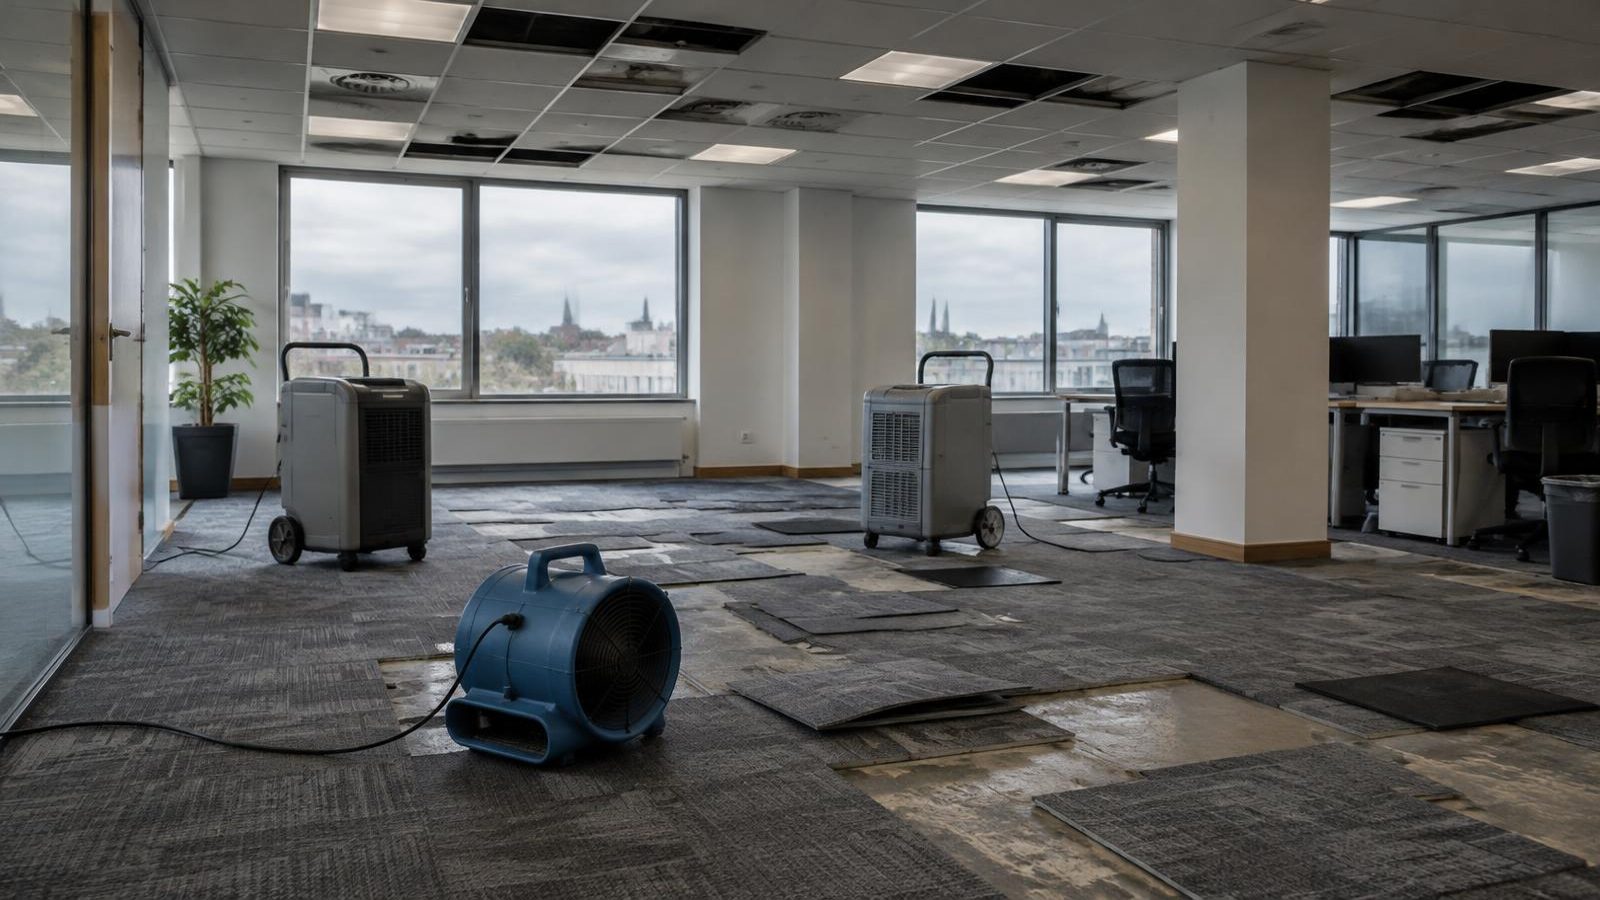
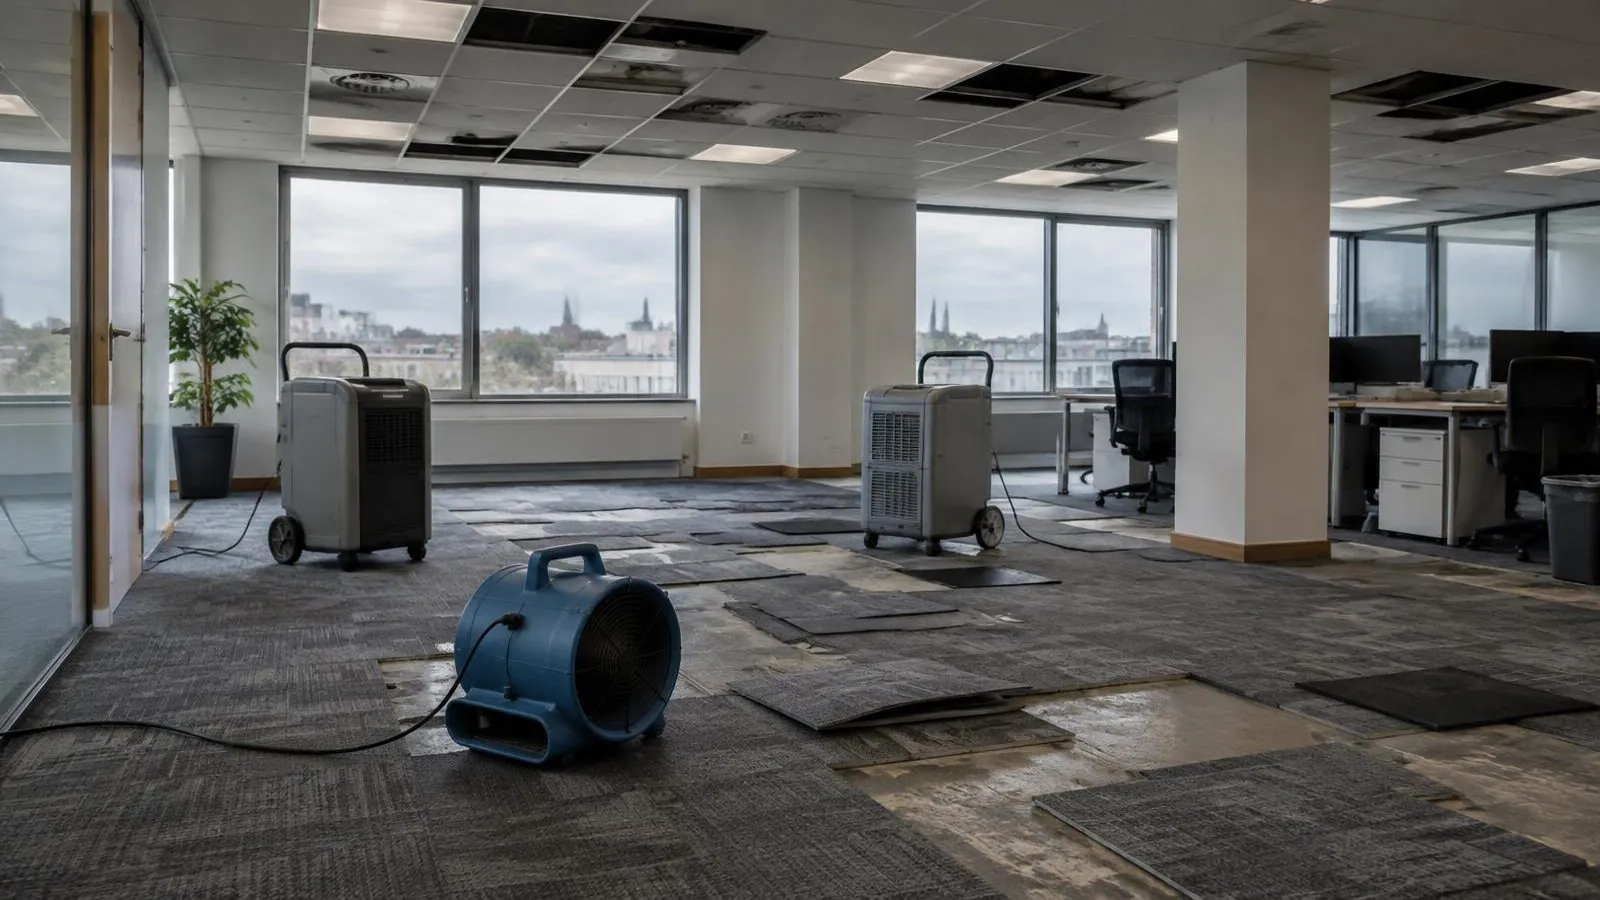
Consider an illustrative example. A 25-person consultancy rents two floors of a multi-let office building. An escape of water damages ceilings, flooring, IT equipment and paper files on its floors, and the space is closed for remedial works.
- The contents section of the consultancy's policy pays for damaged furniture, equipment and records, subject to the policy terms.
- Business interruption pays for temporary serviced office space, equipment hire and IT recovery as increased cost of working.
- It also pays the reduction in gross profit as client work is delayed, while salaries and other continuing costs are still met.
- If the works and lost client relationships mean income takes 15 months to return to normal, a 12-month indemnity period would leave the last three months uninsured.
This example is for illustration only. How any claim is settled depends on the policy wording, the sums insured and the facts of the loss.
Independent Office Insurance Advice
Taurus Risk is an independent, FCA-regulated specialist insurance broker. We aim to explain business interruption cover, indemnity periods and sums insured for offices in plain terms and to support clients through renewals and claims.
- Access to UK insurers that write office and professional premises risks
- Office policy wordings explained in plain terms
- Support from a named broker
A response within 24 working hours, no obligation
Choosing the Indemnity Period
The indemnity period is often the most important decision in a business interruption policy. It is the maximum period of cover, and it should reflect how long it would take for the business to return to the position it would have been in without the loss, not just how long repairs take.
For an office business, consider:
- How long it would take to find, fit out and move into replacement premises
- Lead times for specialist equipment, IT infrastructure and furniture
- The time needed to rebuild lost work, records and the client pipeline
- Whether clients lost during the disruption would come back
12 months is commonly selected, but many businesses find 18, 24 or 36 months more realistic once fit-out, landlord works and client recovery are taken into account. A longer indemnity period costs more, but it is often the difference between a claim that covers the whole recovery and one that stops part way through.
Getting the Sum Insured Right
Business interruption sums insured are frequently set too low. The most common reasons are:
- Confusing accounting and insurance gross profit. Insurance gross profit is generally turnover less specified variable costs, such as purchases, so it usually includes most overheads and is often much higher than the gross profit figure in your accounts.
- Not projecting forward. The sum insured should reflect the income expected over the indemnity period, including planned growth, not last year's figures.
- Not scaling for longer indemnity periods. If the indemnity period is 24 months, the sum insured generally needs to reflect 24 months of gross profit, not 12.
Where an average condition applies, underinsurance can reduce a claim proportionately. Some insurers offer cover on a declaration-linked basis, where you declare an estimated figure, the insurer provides an uplift on it and the premium is adjusted once actual figures are known, which helps avoid average. Your accountant and broker can work through the calculation together.
For offices that could relocate quickly, increased cost of working only cover may be a lower-cost alternative. It pays the extra costs of keeping the business running, but not lost profit.
What It Costs
Business interruption is usually bought as part of an office or commercial combined package rather than as a standalone policy. The premium depends on the sum insured, the indemnity period, the type of business, the premises and the extensions selected. Our office insurance cost guide and office insurance premium factors guide explain how insurers price office risks, and our guide to reducing office insurance costs covers how to keep the premium efficient.
If you own office space and let it to tenants, the equivalent protection is loss of rent insurance.
The Verdict
If your office business would lose income, keep paying costs or lose clients during a long disruption, business interruption insurance is generally worth having, and the bigger risk is setting it up too thinly rather than not buying it. If you are fully remote with low fixed costs, a more limited structure, such as increased cost of working only, may be enough. Either way, the indemnity period and sum insured matter more than whether the cover appears on the schedule.
Our office insurance team can help you work through both. If you ever need to use the cover, our guide to making a business insurance claim explains what insurers look for, and business risk management explained covers planning for the events most likely to interrupt trading.
Frequently Asked Questions
Is business interruption insurance worth it for an office?
For most office businesses, yes. Property insurance pays for physical damage, but business interruption cover replaces lost income and funds continuing costs such as salaries and rent while the business recovers. It is worth less to fully remote businesses with low fixed costs that could relocate immediately.
Does business interruption insurance cover cyber attacks or IT outages?
Generally not under a standard property-triggered policy, which needs physical damage by an insured peril. Loss of income from a cyber attack or system failure is usually insured under a cyber insurance policy with its own business interruption section.
What indemnity period should an office business choose?
Choose a period that reflects how long the business would take to fully recover, including finding and fitting out new premises, replacing equipment and rebuilding client work. 12 months is common, but 18 to 36 months is often more realistic.
Does business interruption insurance pay staff salaries?
Salaries are usually protected as part of the insured gross profit, because they are a cost the business continues to meet while income is reduced. Some policies insure payroll separately. Check how your policy is structured.
Is business interruption insurance a legal requirement?
No. Business interruption insurance is not compulsory in the UK, although lenders, landlords or contracts may sometimes expect it. Employers' liability is the main compulsory cover for businesses with staff.
What is the difference between business interruption and loss of rent insurance?
Business interruption protects a trading business's income after insured damage. Loss of rent protects a landlord's rental income when insured damage makes a let property unusable.