PageID: insights-high-value-home-insurance

    We use cookies to analyse traffic and personalise content. Privacy Policy

    We use cookies

    GDPR Compliant

    We use cookies and similar technologies to enhance your browsing experience, analyse website traffic, and provide personalised content. By clicking "Accept All", you consent to our use of cookies. Learn more in our Privacy Policy

    Back to Insights
    Private Client
    high-value home insurance
    listed building insurance

    High-Value Home Insurance: What It Is and Who Needs It

    High value home insurance is buildings and contents cover designed for larger homes, valuable possessions and more complex lives. Compared with a standard policy, it typically offers higher limits, broader cover for art, jewellery and watches, worldwide protection and more generous claims settlement. It suits owners whose rebuild costs or contents exceed what mainstream policies are built for.

    Our private client insurance team arranges this cover for homeowners and collectors across the UK.

    By Taurus Risk · Published

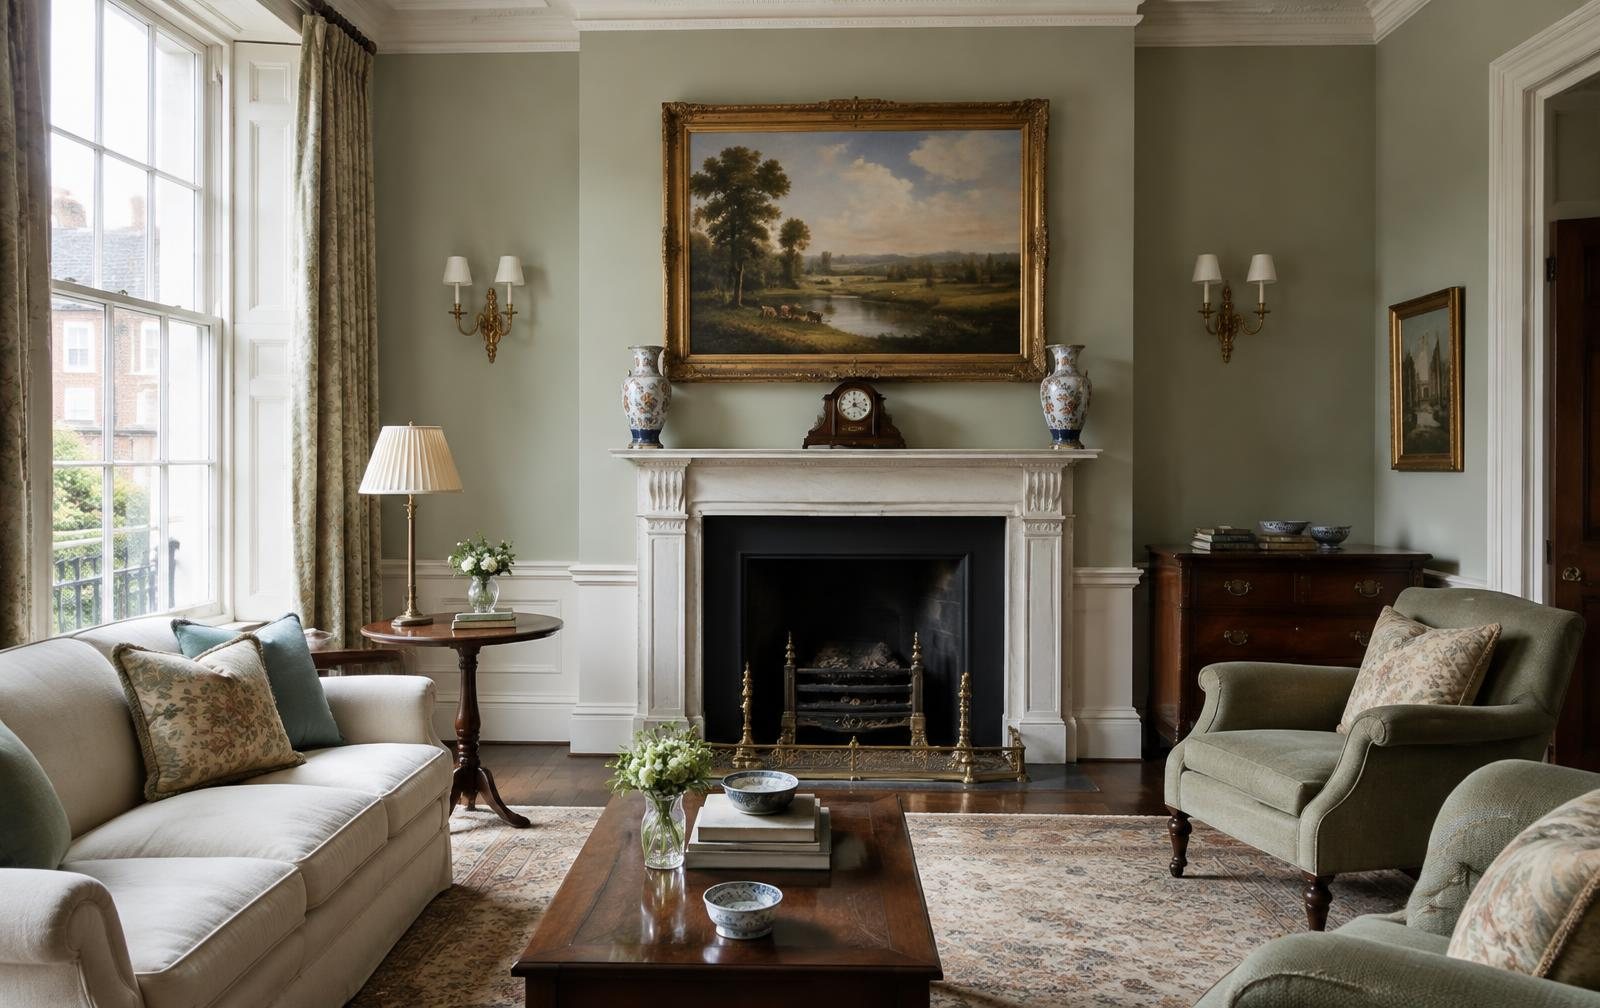
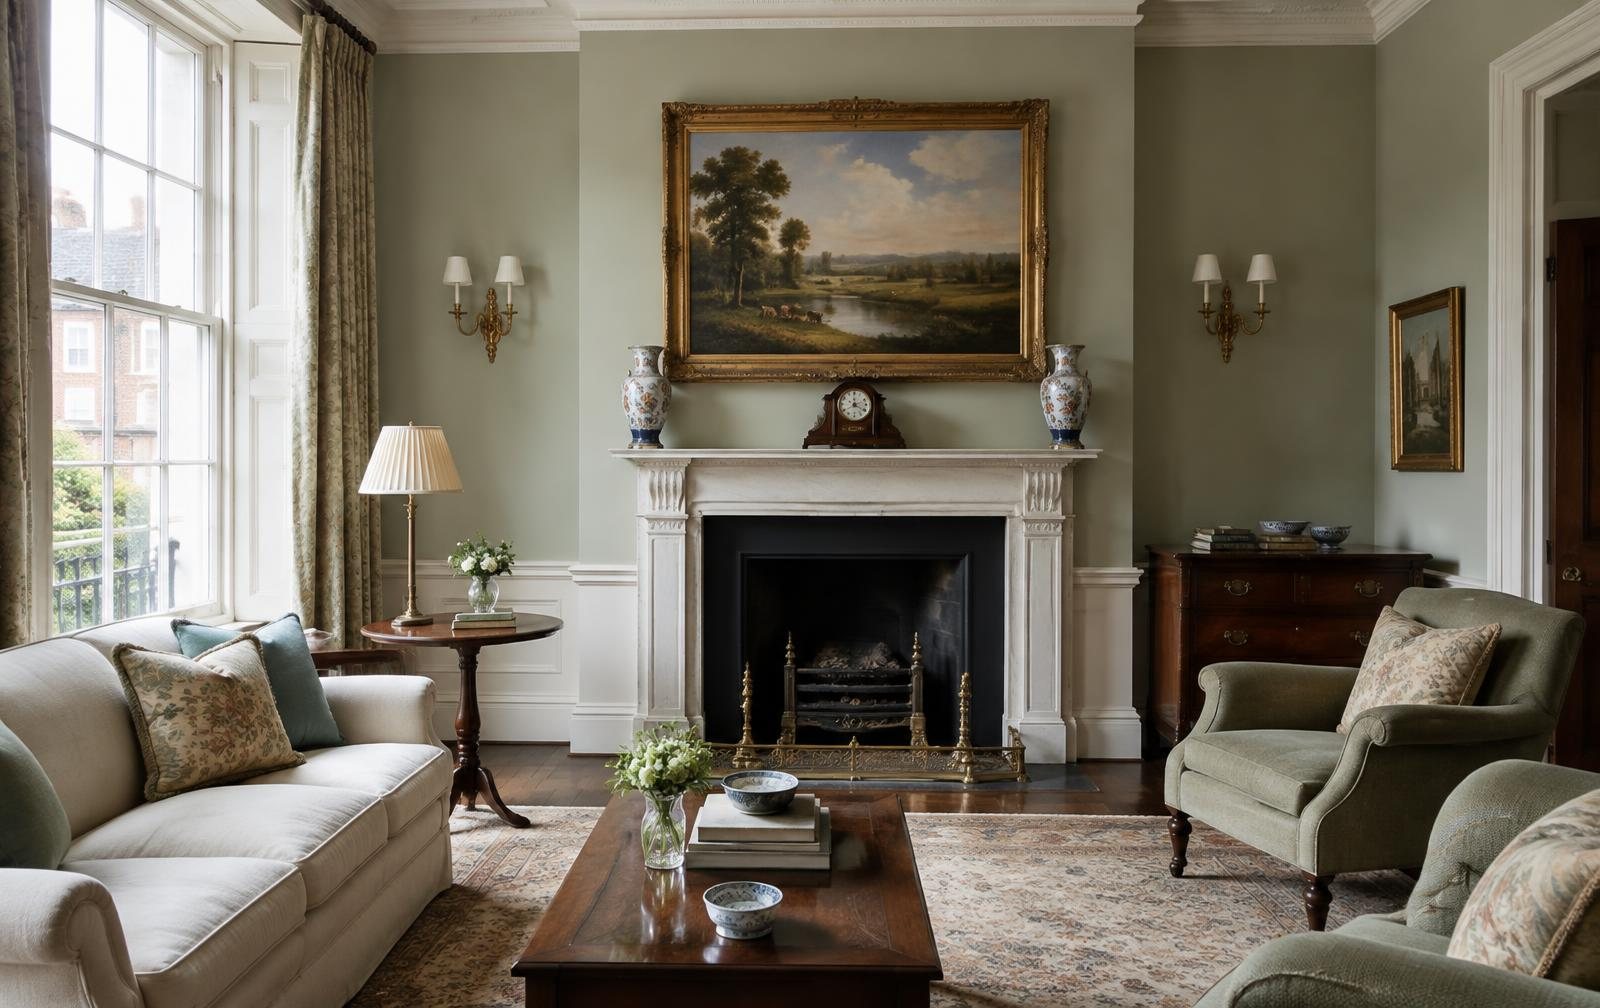
    Drawing room with fine art and antiques in a period townhouse

    What is high value home insurance?

    High value home insurance is home insurance designed for properties and possessions that exceed the limits of a standard household policy. The cover is usually broader, the limits higher and the claims service more personal.

    Many policies combine buildings, contents, valuables, fine art and personal liability in one document. Some also include, or can add, cover for second homes, homes abroad, personal cyber risks and collections. The aim is to protect the full value of what you own without gaps between separate policies.

    Insurers in this market include specialist divisions of larger groups and firms that focus on private clients. They usually distribute through brokers, though some also deal directly.

    What is classed as a high-value home?

    There is no fixed definition. A home is "high value" for insurance purposes when its rebuild cost, contents or valuables exceed what an insurer's standard product is designed to cover.

    Insurers draw that line in different places, and publish it in different ways. For example:

    • Some insurers' online home quotes stop at set limits on rebuild cost, contents value and property age. Above those limits, you'll usually be asked to speak to someone.
    • Some high-value ranges are designed for homes with contents above a set threshold.

    The threshold is about rebuild cost and contents, not the price the house would sell for. A modest-looking period house with fine panelling, a valuable art collection or significant jewellery can be a high-value risk. Equally, an expensive flat in central London may have a relatively low rebuild cost.

    How does high-value home insurance differ from a standard policy?

    The main differences are in limits, how valuables are settled, where cover applies and how claims are handled. The exact features vary by insurer, so it's worth comparing wordings.

    FeatureStandard home policy (typical)High-value home policy (typical)
    Sums insuredSet for average-sized homes; online quotes often cappedHigher limits for buildings and contents
    Single-article limitLower limit per item, with valuables above it to be declaredHigher per-item limits; scheduled items can be listed
    ValuablesOften limited or add-on coverArt, jewellery, watches and collections cover built in or easily added
    Settlement basis for valuablesOften replacement, subject to limitsAgreed value commonly available for scheduled items
    Cover away from homeOften an add-on, with time limitsWorldwide cover for possessions commonly included
    Alternative accommodationIncluded, usually with a limitTypically more generous, to reflect a comparable home
    RebuildReinstatement to sum insuredReinstatement like for like, with specialist trades for period features
    Risk surveysRareCommon, with security and valuation advice
    Personal liabilityStandard limitOften higher limits, with options for wider liabilities

    Higher single-article limits

    A single-article limit is the most a policy will pay for one item, pair or set unless it is specifically listed. Standard policies have relatively low limits.

    Insurers publish different figures. Some cover individual items or sets up to a relatively high figure as standard, while others set lower limits for jewellery and watches. Anything above the limit should be declared and listed.

    Agreed value for valuables

    Many high-value policies allow scheduled items to be insured on an agreed value basis. Agreed value means the insurer and the client agree the value in advance, usually supported by a professional valuation.

    The benefit is certainty, because it reduces disputes about value after a loss. Our guide to valuing art and jewellery for insurance explains how valuations work.

    Worldwide cover

    High-value policies commonly cover possessions taken away from home anywhere in the world. Many include worldwide cover for theft, loss and damage to possessions as standard.

    Time limits and conditions can apply, so check the wording, particularly if you spend long periods abroad.

    Alternative accommodation

    If your home cannot be lived in after an insured loss, the policy pays for somewhere else to stay. Some high-value policies extend this to domestic pets as well.

    For a large home, the cost of comparable accommodation for months can be significant. Check how the policy limits this cover.

    Rebuilding like for like

    A high-value home often has features that standard builders cannot replicate: stonework, joinery, decorative plaster or a listed structure. Reinstatement should use matching materials and appropriate specialist trades.

    That only works if the sum insured is right. Our guide to underinsurance in high-value homes explains why rebuild valuations matter. If your home is listed, see our listed building insurance page.

    Risk surveys

    Specialist insurers commonly survey high-value homes. A surveyor visits to understand the property, review security and fire protection, and sometimes advise on values.

    Some insurers' surveyors also advise on improvements such as alarm systems and door locks. Surveys can help clients improve their protection, and they give insurers confidence in the risk.

    Who needs high-value home insurance?

    It typically suits people whose homes or possessions fall outside standard product limits, or whose lives are more complex. Common examples include:

    • owners of large or period homes with high rebuild costs;
    • collectors of art, antiques, wine, watches or jewellery;
    • people with more than one home, in the UK or abroad;
    • owners of country houses and estates (see our guide to country house and estate insurance);
    • families who travel often with valuable possessions;
    • people employing household staff, which can raise employers' liability questions.

    If you are unsure whether you have outgrown a standard policy, compare your rebuild cost, contents total and most valuable items with your current limits.

    Which high-value home insurance company is best?

    There is no single best insurer. The right one depends on your property, collection, claims history, location and how you like to be looked after.

    The specialist market includes several insurers with private client ranges. They differ in appetite for certain property types, how they treat valuables, their excesses and their claims approach. A home that one insurer declines or loads heavily may suit another well.

    When comparing, look beyond the premium:

    • the policy wording and its exclusions;
    • single-article limits and how valuables are settled;
    • how alternative accommodation and liability are limited;
    • what risk management and valuation support is provided;
    • the insurer's reputation for handling complex claims.

    Why use a broker for high-value home insurance?

    A broker compares insurers, presents your home and possessions accurately and explains the differences in cover. That matters more here than for a standard policy, because wordings vary more and the stakes are higher.

    A broker can also coordinate valuations, keep schedules of valuables up to date and handle notifications when circumstances change. At claim time, they can support you through the process.

    Illustrative example: a client has a London house, a holiday home in Portugal and a jewellery collection, each insured separately. Bringing them under one high-value programme, where insurers allow, can reduce gaps between policies and make renewals simpler. Whether that is possible depends on the insurers' appetite and the locations involved.

    What to have ready for a quote

    • The address of each home, and whether any is listed (with its grade or category).
    • Construction of the walls, roof, floors and framing, and the age of each part.
    • A current rebuild valuation for each home: its figure, when it was done and by whom.
    • Whether an electrical inspection has been carried out, and when.
    • Heating, fire and security protections, including alarms and safes.
    • An estimate of total contents value.
    • A list of your most valuable items, with recent valuations or receipts.
    • How each home is occupied, and any periods it is left empty.
    • Any planned or ongoing works.
    • Your claims history for the last five years.
    • Details of any second homes, household staff and regular travel.
    • Your current policy schedules and renewal dates.
    Frequently asked questions

    How Taurus can help

    We compare specialist private client insurers, present your homes and collection properly and explain the differences between wordings in plain English. Where insurers allow, we bring your homes, contents and valuables into one programme, with agreed values for scheduled items. We cannot promise cover or a price, but we can show you the realistic options.

    Read more about our high-value home insurance service. To talk through your cover, call 020 3958 2070, email Enquiries@Taurus-Risk.com or request a quote. We aim to give you a response within 24 working hours.

    Get a private client quote

    This guide provides general information, not individual insurance or legal advice. Cover is subject to policy terms, conditions and exclusions.

    Related guides

    Underinsurance on high-value homesValuing art and jewellery for insuranceCountry house and estate insurance
    Related Insights

    Private Client Industry Insights

    Stay informed with our latest insights, guides, and expert analysis specifically relevant to the private client sector.

    High-Value Home Insurance: What It Is and Who Needs It
    Private Client

    High-Value Home Insurance: What It Is and Who Needs It

    High value home insurance explained: how it differs from a standard policy, what counts as a high-value home and how to compare insurers. Talk to a broker.

    Pairs and Sets Cover Explained
    Private Client

    Pairs and Sets Cover Explained

    Pairs and sets cover explained: what you are paid when one earring, chair or vase is lost, and how better wordings protect the set. Talk to Taurus.

    Valuing Art, Jewellery and Collections for Insurance
    Private Client

    Valuing Art, Jewellery and Collections for Insurance

    Art valuation for insurance in the UK: what value to insure, who should value, how often to revalue and records to keep. Ask Taurus to check your cover.

    Underinsurance in High Net Worth Homes: Rebuild, Contents and Valuables
    Private Client

    Underinsurance in High Net Worth Homes: Rebuild, Contents and Valuables

    Underinsurance in high net worth homes explained: how average cuts claims, where sums insured go wrong, and a yearly checklist. Ask Taurus for a review.

    Country House and Estate Insurance
    Private Client

    Country House and Estate Insurance

    Country house insurance explained: how to cover the main house, cottages, staff, land and art under one programme, with no gaps. Speak to Taurus.

    FCA Regulated Broker

    Independent High-Value Home Insurance Advice

    We compare specialist private client insurers, present your homes and collection properly and explain the differences between wordings in plain English.

    • Specialist private client insurer comparison
    • Homes, contents and valuables considered together
    • Policy wording and valuation support
    Get a Quote

    A response within 24 working hours, no obligation

    Related Specialisms

    Explore the specialist cover most relevant to this guide.

    high-value home insurance

    High value home insurance explained: how it differs from a standard policy, what counts as a high-value home and how to compare insurers. Talk to a broker.

    View high-value home insurance

    listed building insurance

    High value home insurance explained: how it differs from a standard policy, what counts as a high-value home and how to compare insurers. Talk to a broker.

    View listed building insurance

    residential property insurance

    Cover for let homes and residential property holdings.

    View residential property insurance
    CallGet a Quick Quote
    32 Reviews
    REVIEWS.io
    5 Rating
    32 Reviews
    Shannon
    Verified Customer
    Billy was very helpful in helping me arrange my insurance. He was prompt when replying to emails, knowledgeable and friendly. Thank you Taurus Risk Management!
    Edward
    Verified Customer
    V. responsive and helpful in pulling together and agreeing a quote for buildings insuruance. Would recommend
    Jack
    Verified Customer
    We engaged Taurus Risk to advise on and place cover for a large residential building in North London. Thomas in particular was fantastic, provided timely and well thought out advice, and more importantly advised us appropriately for the risk we needed to cover. We ended up moving from our previous broker as the service and options for cover was far better than what our previous broker was offering. I stand behind and would definitely recommend Taurus Risk.
    Robert
    Verified Customer
    Chris was brilliant - he really helped us out to find a competitive quote when we were having trouble with other brokers. He turned a quote around in record time and was diligent and helpful. We will definitely be using Taurus again next year.
    Beverley
    Verified Customer
    Our needs were assessed and understood. We received a timeous and properly considered solution in a very short space of time. An absolute pleasure.
    Camilla
    Verified Customer
    Chris was a pleasure to deal with. He was very responsive, provided an excellent service and was professional. I would recommend Taurus who are reliable and efficient, and get you the best deal.
    Raj
    Verified Customer
    Very professional took time to listen and set my cover accordingly pleaseure to deal with. Thank you!
    Imran
    Verified Customer
    I found Taurus online last year and this is my second year I am using Taurus for my Insurance renewal. Chris and Billy have both been very good to me and our relationship is not just about me asking for a insurance policy but we have a general chat which makes a huge difference when deciding should I shop around or actually Taurus take care of me so why should I have to look elsewhere. The pricing is competitive and I receive good advice. I am happy I have found an excellent organisation
    Sairah
    Verified Customer
    Had a very competitive quote from Chris Foster - multi property, including rent cover. Gone ahead with the policy, and hope the underwriters will be a good solution, should anything occur.
    Jonathon
    Verified Customer
    Tom and Billy of Taurus Risk Management provide a highly personalised and commercially focused service. They take the time to ensure that clients fully understand their insurance policies and that cover arrangements are aligned with their specific requirements. Their approach is centred on understanding each client's budget, objectives, and any operational constraints, enabling them to source the most suitable and competitive insurance solutions available. Combined with their professional, approachable, and responsive manner, they instil confidence throughout the process and make it clear that you are working with a trusted and knowledgeable team. I would have no hesitation in recommending Taurus Risk Management to individuals and businesses seeking expert insurance advice and exceptional client service.
    Suzie
    Verified Customer
    Quick and easy process, Chris was very helpful in ensuring we get the right cover for a reasonable price. Would highly recommend.
    Clare
    Verified Customer
    Chris helped me secure buildings insurance for a group of 6 residential buildings - a mix HMO and flats, he obtained several quotes for me to consider and the price was very competitive. The service was brilliant and I would definitely use Taurus risk management again.
    Alexandra
    Verified Customer
    I recently purchased house and travel insurance through Taurus Risk and had an excellent experience. From the initial communication to their prompt and efficient responses, the team demonstrated a high level of professionalism throughout. They addressed all of my questions quickly and provided clear, valuable advice. I would highly recommend Taurus Risk to anyone seeking a reliable and knowledgeable insurance broker.
    Warren
    Verified Customer
    It was an absolute pleasure working with Taurus. From the beginning it felt like the team had a genuine interest in my priorities and what was most important. Looking forward to our partnership together.
    Meg
    Verified Customer
    Team Taurus did a great job - providing fantastic client service. We are very happy with our insurance coverage.