PageID: insights-country-house-estate-insurance

    We use cookies to analyse traffic and personalise content. Privacy Policy

    We use cookies

    GDPR Compliant

    We use cookies and similar technologies to enhance your browsing experience, analyse website traffic, and provide personalised content. By clicking "Accept All", you consent to our use of cookies. Learn more in our Privacy Policy

    Back to Insights
    Private Client
    high net worth home insurance
    listed building insurance

    Country House and Estate Insurance

    Country house insurance covers a large rural home and, often, everything around it: cottages, outbuildings, staff, land, contents and art. The aim is one coordinated programme with accurate rebuild values, the right liability covers and no gaps. Listed status, letting and rural risks all shape how insurers view the estate.

    By Taurus Risk · Published

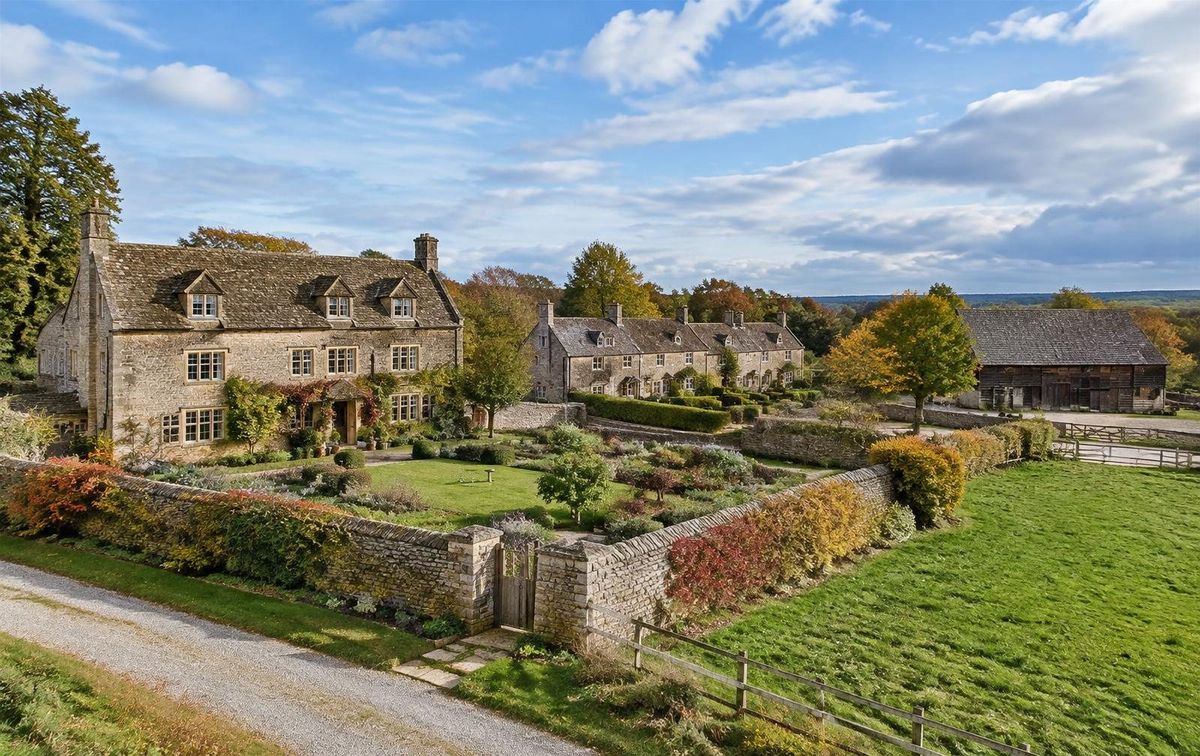
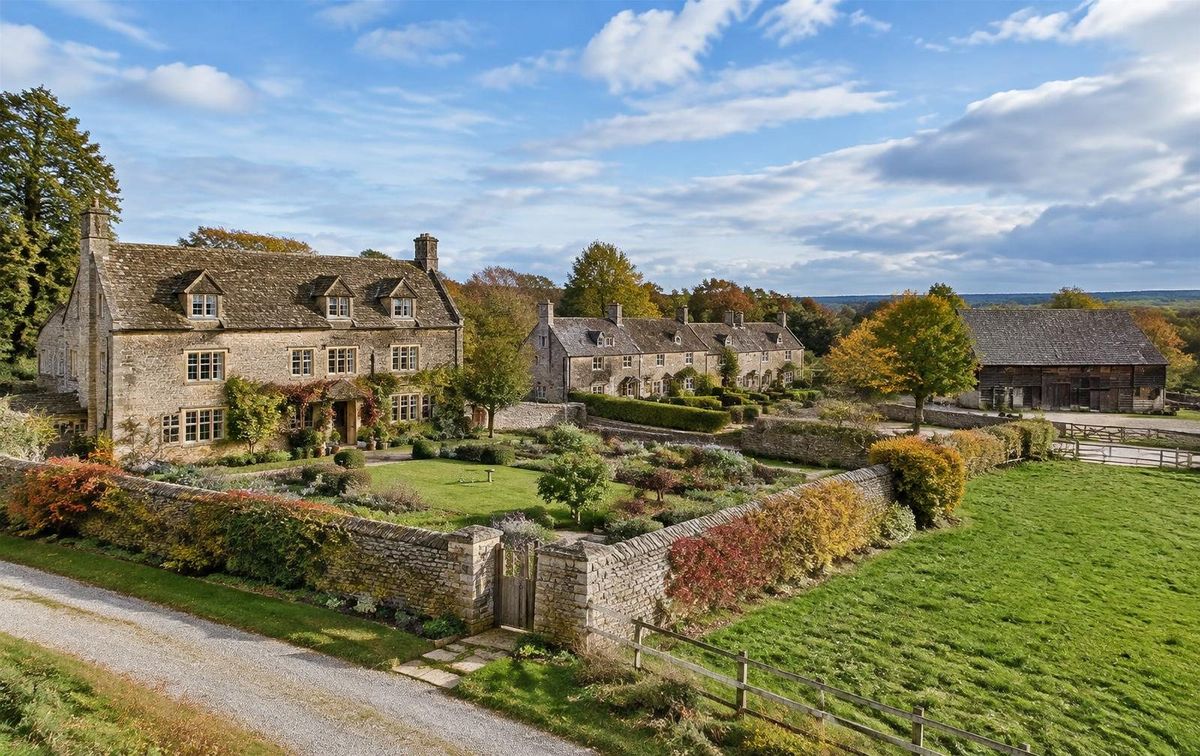
    Stone country house with estate cottages and a barn, illustrating country house insurance

    What is country house insurance?

    Country house insurance is home insurance designed for larger rural properties and the estates around them. It typically brings together buildings, contents, valuables and liabilities for the main house, and can extend to other buildings and land.

    The difference from a standard home policy is scale and complexity. It's important that higher sums insured, multiple buildings, staff and public access are all reflected in the cover.

    Where possible, bringing everything into one programme reduces the risk of gaps. It also makes renewals, claims and valuations easier to manage.

    What should an estate insurance programme cover?

    An estate programme should cover everything you own, occupy or are responsible for. The table below sets out the usual components and what to check for each.

    ComponentTypical coverWhat to check
    Main houseBuildings, contents, valuablesRebuild cost, listed status, security, fire protection
    Owner's or family cottagesBuildings and contentsEach cottage valued separately; occupancy
    Let cottagesLandlord buildings, loss of rent, property owners' liabilityTenancy type; contents provided
    Holiday letsHoliday let cover, including guest liabilityLetting periods, management, safety
    OutbuildingsBarns, stables, garages, workshops, glasshousesContents stored; any business or farm use
    GroundsWalls, gates, drives, pools, tennis courtsIncluded in buildings sum insured or listed separately
    StaffEmployers' liabilityWho employs them, and whether cover is required
    Land and public accessProperty owners' and public liabilityFootpaths, events, shoots, lakes, trees
    Contents and artContents, fine art, collectionsValuations, single-article limits, pairs and sets
    VehiclesPrivate motor and estate vehiclesUse on public roads and estate land

    How should each building be valued?

    Each building should be valued on its own rebuild cost, including professional fees and debris removal. Market value is not the right measure, and an estate may include very different building types.

    A country house can cost far more to rebuild than its size suggests, especially with stone, oak, lime or thatch. Barns and cottages need their own figures too. A professional reinstatement cost assessment is the most reliable basis.

    Our guide to underinsurance in high-value homes explains the methods and the risks of getting it wrong.

    How does listed status affect country house insurance?

    Many country houses are listed or of traditional construction, such as solid stone, timber frame or thatch, and both shape how they are rebuilt. For listed houses, insurers will want to know the grade and what the listing covers.

    Listing can reach beyond the main house. In Wales, Cadw explains that listing covers the entire building, inside and out, and any object or structure within the curtilage constructed before 1 July 1948. That can include walls, stables, gate piers and garden buildings.

    Historic England notes that 92% of listed buildings in England are Grade II, with 5.5% Grade II* and 2.5% Grade I. Our listed and heritage building insurance page covers this in more depth.

    How are estate cottages and holiday lets insured?

    Estate cottages are insured according to who lives there. Family or owner-occupied cottages can often sit within the main home policy, but let property usually needs landlord cover.

    Long-let cottages need residential property insurance on a landlord basis, property owners' liability and, ideally, loss of rent. See our guide to loss of rent insurance.

    Holiday lets bring guests onto the estate. They need cover designed for short-term letting, including liability to guests. Our guide to landlord insurance for holiday lets explains the main points.

    Some high-value home policies allow limited letting of the home itself. One high-value wording, for example, treats occasional hiring of the home and gardens to others as incidental business, up to a set annual income limit. Anything beyond the policy's allowance should be insured separately.

    Do I need employers' liability insurance for domestic staff?

    Possibly. It depends on how staff are engaged and whether they work only for you, so take advice before anyone starts.

    The Employers' Liability (Compulsory Insurance) Act 1969 requires every employer carrying on any business in Great Britain to insure. The cover is for injury or disease to employees arising from their employment in that business. Gov.uk states that employers can be fined £2,500 for every day they are not properly insured.

    For domestic help, the Health and Safety Executive's guidance (HSE40) calls this "one difficult area". It says you will probably not need employers' liability insurance for cleaners or gardeners who work for more than one person. For someone who works only for you, it says "you may be required to take out insurance to protect them."

    Estates often employ housekeepers, gardeners, gamekeepers or estate managers full-time. Where staff work for an estate company or a business on the estate, the 1969 Act is more likely to apply. High-value home policies may include liability to domestic staff, so check the wording and limit.

    What liability risks come with land?

    Owning land means duties to people who come onto it, whether invited or not. Property owners' and public liability cover responds to claims for injury or damage to third parties.

    Typical estate exposures include:

    • Public footpaths and bridleways crossing the land.
    • Trees near roads, paths or neighbouring property.
    • Lakes, ponds and rivers.
    • Livestock and fencing.
    • Events such as weddings, open gardens, fêtes or shoots.
    • Contractors working on the estate.

    Disclose activities clearly. A wedding venue, a farm shop or a regular events programme may need hospitality insurance or other commercial cover alongside the private policy.

    What about contents, art and vehicles?

    Country houses often hold significant collections. Contents and art should be valued properly, with high-value items specified above the policy's single-article limits.

    Pairs and sets, such as chairs, portraits or porcelain, need particular attention. See our guide to valuing art, jewellery and collections for insurance.

    Vehicles should be reviewed alongside the property programme. Cars used on public roads need motor insurance, and estate vehicles used on land may need separate consideration.

    What rural risks do insurers focus on?

    Fire, flood and theft are the main concerns. Rural properties may be further from the fire service, may have private water supplies and are often harder to secure.

    Fire. Insurers will ask about wiring, heating, chimneys, wood burners, thatch and fire detection. Outbuildings with fuel, machinery or hay add to the risk.

    Flood. Rivers, lakes and surface water can all affect an estate. Flood Re, the UK scheme that helps make flood cover more available for homes, has its own eligibility criteria. It requires homes to have been built before 1 January 2009 and to be used for private residential purposes. Flood Re expects farmhouses and cottages to be eligible, but not farm outbuildings.

    Theft. Outbuildings are often a weak point. Intruders may see them as easy wins, and unsecured ladders can give access to upper floors. Layered security, from the perimeter inwards, is the usual approach.

    Unoccupancy. Second homes and empty cottages need care. See unoccupied property insurance.

    What to have ready for a quote

    • A plan or list of every building, with its use and who occupies it.
    • Listed status and grade or category for each building, where relevant.
    • Construction of the walls, roof, floors and framing, and the age of each building.
    • Rebuild assessments for the main house, cottages and outbuildings: when done and by whom.
    • Whether an electrical inspection has been carried out on each building, and when.
    • Heating, fire and security protections, including alarms and any on-site water supply.
    • Any buildings unoccupied, and any planned or ongoing works.
    • Details of lettings (long lets and holiday lets) and the rent each produces.
    • Estate staff, their roles and the annual wageroll.
    • Events, shoots, weddings and any other business activity, with the income each brings.
    • Contents values, and valuations for art, antiques and jewellery above single-article limits.
    • Your claims history for the last five years.
    • Your current schedules and renewal dates.
    Frequently asked questions

    How Taurus can help

    Taurus is an independent, FCA-authorised broker. We review country houses and estates as a whole and identify gaps between buildings and covers. We then aim to bring them under one programme, with agreed values for art and scheduled items where available.

    We compare insurers with appetite for large, listed and traditionally built rural property. Visit our private client insurance page, read about high-value home insurance, or request a quote. You can also call 020 3958 2070 or email Enquiries@Taurus-Risk.com, and we aim to give you a response within 24 working hours.

    Get a private client quote

    This guide provides general information, not individual insurance or legal advice. Cover is subject to policy terms, conditions and exclusions.

    Related guides

    High-Value Home Insurance: What It Is and Who Needs ItUnderinsurance on high-value homesValuing art and jewellery for insurance
    Related Insights

    Private Client Industry Insights

    Stay informed with our latest insights, guides, and expert analysis specifically relevant to the private client sector.

    High-Value Home Insurance: What It Is and Who Needs It
    Private Client

    High-Value Home Insurance: What It Is and Who Needs It

    High value home insurance explained: how it differs from a standard policy, what counts as a high-value home and how to compare insurers. Talk to a broker.

    Pairs and Sets Cover Explained
    Private Client

    Pairs and Sets Cover Explained

    Pairs and sets cover explained: what you are paid when one earring, chair or vase is lost, and how better wordings protect the set. Talk to Taurus.

    Valuing Art, Jewellery and Collections for Insurance
    Private Client

    Valuing Art, Jewellery and Collections for Insurance

    Art valuation for insurance in the UK: what value to insure, who should value, how often to revalue and records to keep. Ask Taurus to check your cover.

    Underinsurance in High Net Worth Homes: Rebuild, Contents and Valuables
    Private Client

    Underinsurance in High Net Worth Homes: Rebuild, Contents and Valuables

    Underinsurance in high net worth homes explained: how average cuts claims, where sums insured go wrong, and a yearly checklist. Ask Taurus for a review.

    Country House and Estate Insurance
    Private Client

    Country House and Estate Insurance

    Country house insurance explained: how to cover the main house, cottages, staff, land and art under one programme, with no gaps. Speak to Taurus.

    FCA Regulated Broker

    Independent High-Value Home Insurance Advice

    We compare specialist private client insurers, present your homes and collection properly and explain the differences between wordings in plain English.

    • Specialist private client insurer comparison
    • Homes, contents and valuables considered together
    • Policy wording and valuation support
    Get a Quote

    A response within 24 working hours, no obligation

    Related Specialisms

    Explore the specialist cover most relevant to this guide.

    high net worth home insurance

    Country house insurance explained: how to cover the main house, cottages, staff, land and art under one programme, with no gaps. Speak to Taurus.

    View high net worth home insurance

    listed building insurance

    Country house insurance explained: how to cover the main house, cottages, staff, land and art under one programme, with no gaps. Speak to Taurus.

    View listed building insurance
    CallGet a Quick Quote
    32 Reviews
    REVIEWS.io
    5 Rating
    32 Reviews
    Shannon
    Verified Customer
    Billy was very helpful in helping me arrange my insurance. He was prompt when replying to emails, knowledgeable and friendly. Thank you Taurus Risk Management!
    Edward
    Verified Customer
    V. responsive and helpful in pulling together and agreeing a quote for buildings insuruance. Would recommend
    Jack
    Verified Customer
    We engaged Taurus Risk to advise on and place cover for a large residential building in North London. Thomas in particular was fantastic, provided timely and well thought out advice, and more importantly advised us appropriately for the risk we needed to cover. We ended up moving from our previous broker as the service and options for cover was far better than what our previous broker was offering. I stand behind and would definitely recommend Taurus Risk.
    Robert
    Verified Customer
    Chris was brilliant - he really helped us out to find a competitive quote when we were having trouble with other brokers. He turned a quote around in record time and was diligent and helpful. We will definitely be using Taurus again next year.
    Beverley
    Verified Customer
    Our needs were assessed and understood. We received a timeous and properly considered solution in a very short space of time. An absolute pleasure.
    Camilla
    Verified Customer
    Chris was a pleasure to deal with. He was very responsive, provided an excellent service and was professional. I would recommend Taurus who are reliable and efficient, and get you the best deal.
    Raj
    Verified Customer
    Very professional took time to listen and set my cover accordingly pleaseure to deal with. Thank you!
    Imran
    Verified Customer
    I found Taurus online last year and this is my second year I am using Taurus for my Insurance renewal. Chris and Billy have both been very good to me and our relationship is not just about me asking for a insurance policy but we have a general chat which makes a huge difference when deciding should I shop around or actually Taurus take care of me so why should I have to look elsewhere. The pricing is competitive and I receive good advice. I am happy I have found an excellent organisation
    Sairah
    Verified Customer
    Had a very competitive quote from Chris Foster - multi property, including rent cover. Gone ahead with the policy, and hope the underwriters will be a good solution, should anything occur.
    Jonathon
    Verified Customer
    Tom and Billy of Taurus Risk Management provide a highly personalised and commercially focused service. They take the time to ensure that clients fully understand their insurance policies and that cover arrangements are aligned with their specific requirements. Their approach is centred on understanding each client's budget, objectives, and any operational constraints, enabling them to source the most suitable and competitive insurance solutions available. Combined with their professional, approachable, and responsive manner, they instil confidence throughout the process and make it clear that you are working with a trusted and knowledgeable team. I would have no hesitation in recommending Taurus Risk Management to individuals and businesses seeking expert insurance advice and exceptional client service.
    Suzie
    Verified Customer
    Quick and easy process, Chris was very helpful in ensuring we get the right cover for a reasonable price. Would highly recommend.
    Clare
    Verified Customer
    Chris helped me secure buildings insurance for a group of 6 residential buildings - a mix HMO and flats, he obtained several quotes for me to consider and the price was very competitive. The service was brilliant and I would definitely use Taurus risk management again.
    Alexandra
    Verified Customer
    I recently purchased house and travel insurance through Taurus Risk and had an excellent experience. From the initial communication to their prompt and efficient responses, the team demonstrated a high level of professionalism throughout. They addressed all of my questions quickly and provided clear, valuable advice. I would highly recommend Taurus Risk to anyone seeking a reliable and knowledgeable insurance broker.
    Warren
    Verified Customer
    It was an absolute pleasure working with Taurus. From the beginning it felt like the team had a genuine interest in my priorities and what was most important. Looking forward to our partnership together.
    Meg
    Verified Customer
    Team Taurus did a great job - providing fantastic client service. We are very happy with our insurance coverage.