PageID: insights-pairs-and-sets-cover

    We use cookies to analyse traffic and personalise content. Privacy Policy

    We use cookies

    GDPR Compliant

    We use cookies and similar technologies to enhance your browsing experience, analyse website traffic, and provide personalised content. By clicking "Accept All", you consent to our use of cookies. Learn more in our Privacy Policy

    Back to Insights
    Private Client
    high-value home insurance

    Pairs and Sets Cover Explained

    Pairs and sets cover decides what your insurer pays when one item from a matching pair or set is lost or damaged. Many standard policies pay for the lost item plus a fixed share of the undamaged pieces. Better high-value wordings pay for the loss in value of the whole set. Check which basis you have.

    By Taurus Risk · Published

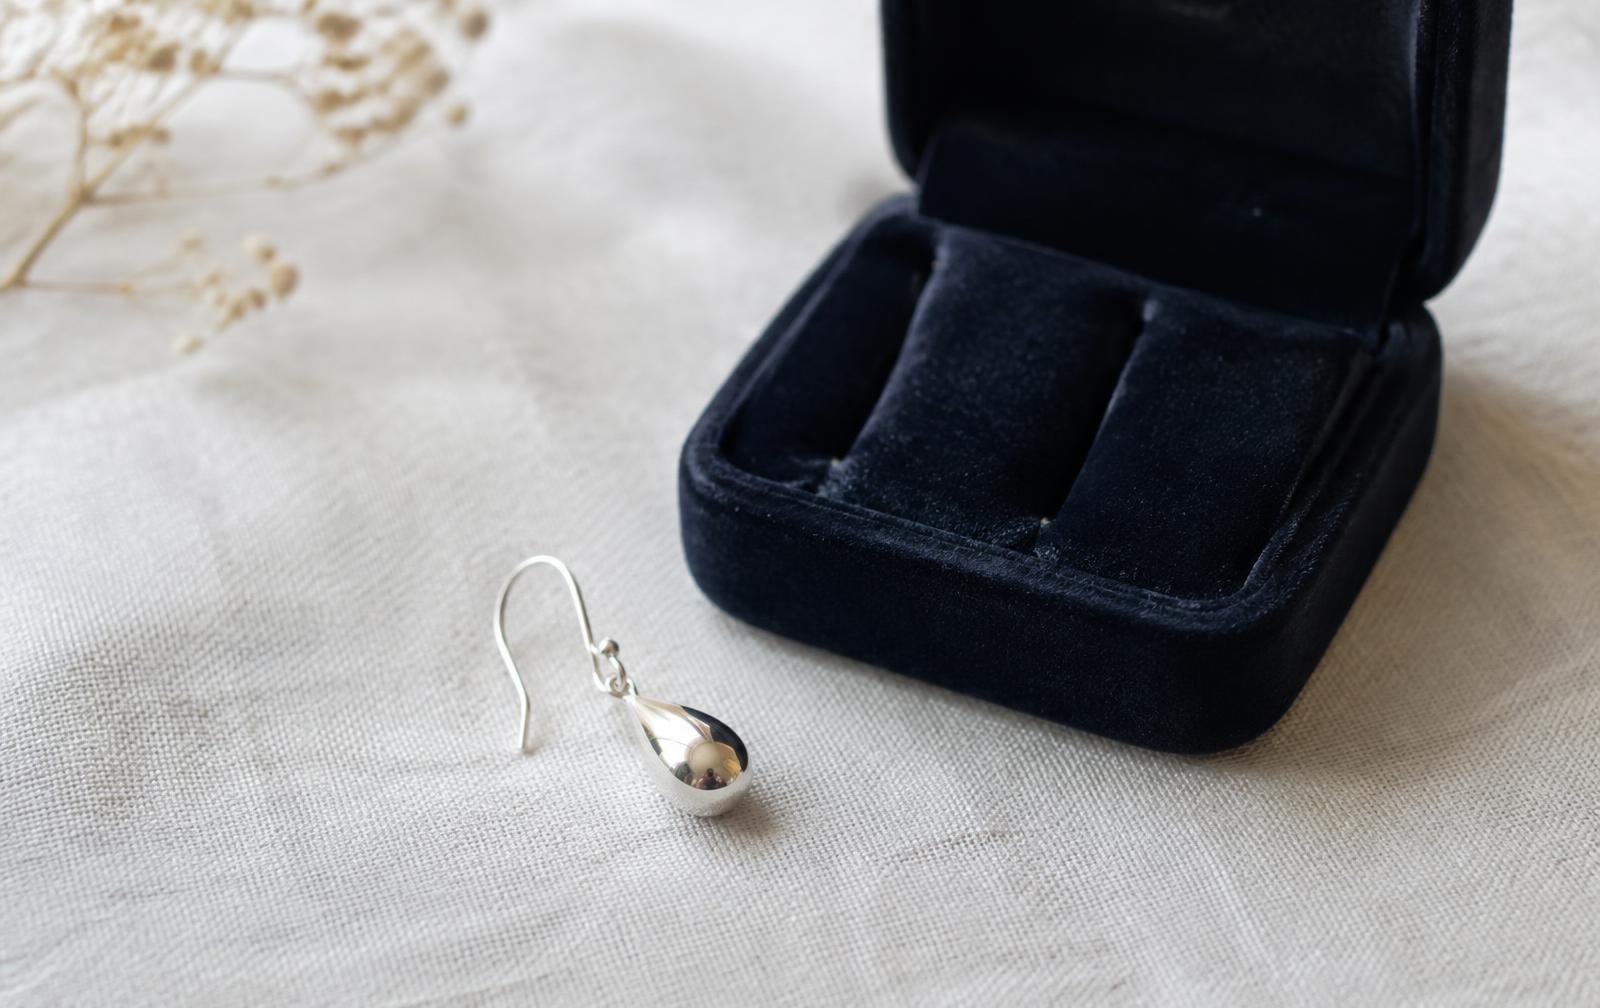
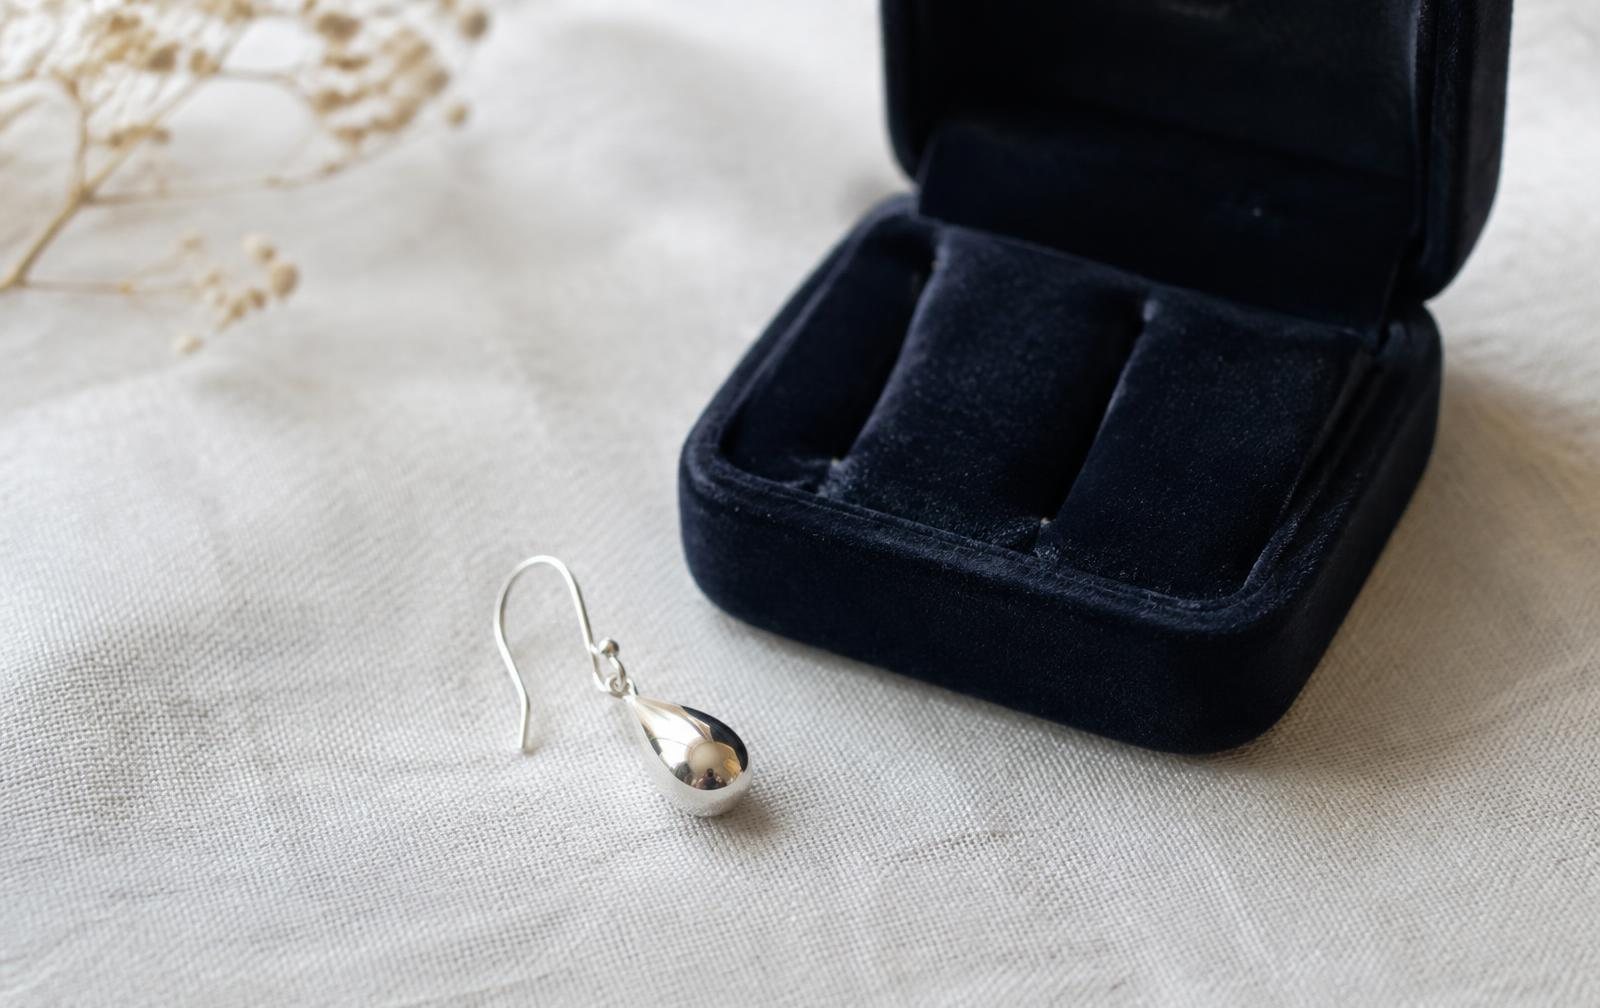
    A single earring beside an empty jewellery box slot, illustrating pairs and sets cover

    What is a pair and set clause?

    A pair and set clause is the part of a home insurance policy that deals with partial loss of a matching group. It tells you whether the insurer pays only for the damaged piece, part of the cost of the undamaged pieces, or the full drop in value.

    The issue is simple. Lose one earring of a pair and the other is worth far less on its own. Damage one chair from a set of twelve and the set may lose value even after the chair is repaired.

    Without specific wording, the starting point is usually the cost of the item actually lost or damaged. The pair and set clause then either confirms that limit or extends it.

    How do insurers word pairs and sets cover?

    There is no single market wording for pairs and sets cover. The two UK policy wordings below show how far apart the approaches can be.

    A standard home policy. One standard home wording pays 50% of the cost of replacing undamaged items that form part of a pair, set, collection or suite. The same 50% basis applies in both its buildings and contents sections. You receive the cost of the damaged item plus half the replacement cost of the undamaged companion pieces.

    A high-value home policy. A typical high-value wording takes a different line. For contents, it pays to repair or replace the damaged component parts. If that is not possible, it pays for the repair, alteration or replacement of the whole pair, set or suite.

    For art and antiques, the same wording goes further. Where an item is worth more because it forms part of a pair or set, the payment takes account of the loss in overall value. If you surrender the undamaged pieces, it pays the full replacement cost of the pair or set, within the policy limits.

    These are examples only. Other insurers use different language and limits, so it's important to read your own policy.

    Pairs and sets versus matching items: what is the difference?

    Pairs and sets cover deals with items valued as a group, such as earrings or a set of chairs. Matching items cover deals with fixtures and finishes that cannot be matched after a repair, such as a run of kitchen units or a bathroom suite.

    Take one standard home wording. Its buildings section covers items of "a matching or uniform design, nature or colour, including carpets." The words "including carpets" appear only in the buildings section, not the contents section. The same wording will not pay for undamaged flooring in adjacent rooms.

    In the high-value wording, the buildings section pays to repair or replace damaged component parts. If that is not possible, it pays for "a replacement pair, set or suite of similar quality and specification." The insurer may then take ownership of the damaged and undamaged parts.

    ExampleUsually treated asWhat can go wrong
    Pair of diamond earringsPair (personal valuables)Policy pays for one earring only, though the survivor has lost most of its value
    Pair of cufflinksPair (personal valuables)As above, often with a single-article limit too
    Set of twelve dining chairsSet (contents or antiques)Repair of one chair is paid, but the set's reduced value is not
    Pair of Chinese vasesPair (art and antiques)Market value of a single vase is far below half the pair
    Fitted kitchen unitsMatching items (buildings)Damaged doors are replaced, but no exact match exists for the rest
    Bathroom suiteMatching items (buildings)Cracked basin cannot be matched, so the suite looks mismatched
    Fitted carpet across roomsMatching items (buildings, in some wordings)Only the damaged room is relaid

    Why do pairs and sets matter so much for valuables?

    Because value often sits in the completeness of the set. A pair of matched antique vases, a parure of jewellery or a set of Georgian silver can be worth far more together than the separate pieces.

    Illustrative example: A pair of vases is valued at £40,000 as a pair. One is broken beyond repair, and a single vase is valued at £12,000.

    Settlement basisWhat is paid (approximately)
    Damaged item only£12,000 for the broken vase
    Damaged item plus 50% of undamaged item£12,000 + £6,000 = £18,000
    Loss in value of the pair£40,000 − £12,000 = £28,000
    Full value on surrender of the survivor£40,000, and the insurer takes the surviving vase

    The figures are round and for illustration only. Actual settlement depends on the wording, the valuation and any limits.

    How do high-value home policies usually improve pairs and sets cover?

    High-value wordings usually pay for the drop in value of the set, not just the lost object. Common improvements include:

    • Loss in value. Payment for the reduction in the overall value of the pair or set.
    • Surrender option. The insurer pays the full value of the set and takes the remaining items.
    • Replacement of the whole set. Where a component cannot be repaired or matched.
    • Specified items. Individually listed pieces settled by reference to the scheduled valuation.

    Not every high-value policy includes all of these, and limits apply. Some wordings cap any one unspecified item, pair or set. One high-value wording, for example, sets that cap at £50,000 for art and antiques and £25,000 for personal valuables.

    Our overview of high-value home insurance explains how these policies differ from standard home cover.

    How should a pair or set be valued and scheduled?

    Value the set as a set. The valuation should describe each component and state the value of the pair or set as a whole. That lets the insurer see what the loss in value would be.

    If the set is above the policy's single-article or unspecified limit, it usually needs to be individually specified. Our guide to valuing art, jewellery and collections for insurance explains what a good valuation includes.

    Keep photographs of each piece and of the set together. Record makers' marks, hallmarks, dimensions and any certificates.

    What should I check in my policy?

    Start with the definitions and the basis of settlement, then check the limits. These questions cover most of it:

    QuestionWhy it matters
    Does the policy pay for loss in value, or only for the damaged item?This is the biggest difference between wordings
    Is there a percentage cap on undamaged items?A 50% basis can leave a large shortfall on valuable sets
    Is there a surrender option?It can turn a partial loss into a full settlement
    What is the limit for any one item, pair or set?Valuable sets can exceed it easily
    Are pairs and sets valued as a unit on the schedule?Specifying each piece separately can understate the set's value
    Is there a matching items clause in the buildings section?Kitchens, bathrooms and flooring are frequent sources of dispute
    Does the clause apply to all sections?Wording may differ between buildings, contents and art

    If your collection has grown, recheck the set values too. Under-valued sets feed into wider underinsurance in high-value homes. Owners of larger properties can also speak to our high net worth home insurance team.

    What to have ready for a quote

    • A list of pairs, sets and suites, with the value of each as a set.
    • Recent valuations, since insurers usually expect values to be kept up to date.
    • Photographs of each piece and of the set together.
    • Makers' marks, hallmarks, certificates and purchase receipts.
    • An estimate of total contents value, and your other high-value items.
    • Where the items are kept, and whether any are lent, displayed or taken abroad.
    • Alarm, safe and other security details at home.
    • Your claims history for the last five years.
    • Your current policy schedule and wording, so we can compare the settlement basis.
    Frequently asked questions

    How Taurus can help

    Taurus is an independent, FCA-authorised broker. We compare high-value home wordings and check how pairs, sets and matching items are treated. We then help you schedule valuable sets at agreed values, ideally under one programme with your home and contents.

    Read more on our private client insurance page or request a quote. You can also call 020 3958 2070 or email Enquiries@Taurus-Risk.com, and we aim to give you a response within 24 working hours.

    Get a private client quote

    This guide provides general information, not individual insurance or legal advice. Cover is subject to policy terms, conditions and exclusions.

    Related guides

    High-Value Home Insurance: What It Is and Who Needs ItValuing art and jewellery for insuranceUnderinsurance on high-value homes
    Related Insights

    Private Client Industry Insights

    Stay informed with our latest insights, guides, and expert analysis specifically relevant to the private client sector.

    High-Value Home Insurance: What It Is and Who Needs It
    Private Client

    High-Value Home Insurance: What It Is and Who Needs It

    High value home insurance explained: how it differs from a standard policy, what counts as a high-value home and how to compare insurers. Talk to a broker.

    Pairs and Sets Cover Explained
    Private Client

    Pairs and Sets Cover Explained

    Pairs and sets cover explained: what you are paid when one earring, chair or vase is lost, and how better wordings protect the set. Talk to Taurus.

    Valuing Art, Jewellery and Collections for Insurance
    Private Client

    Valuing Art, Jewellery and Collections for Insurance

    Art valuation for insurance in the UK: what value to insure, who should value, how often to revalue and records to keep. Ask Taurus to check your cover.

    Underinsurance in High Net Worth Homes: Rebuild, Contents and Valuables
    Private Client

    Underinsurance in High Net Worth Homes: Rebuild, Contents and Valuables

    Underinsurance in high net worth homes explained: how average cuts claims, where sums insured go wrong, and a yearly checklist. Ask Taurus for a review.

    Country House and Estate Insurance
    Private Client

    Country House and Estate Insurance

    Country house insurance explained: how to cover the main house, cottages, staff, land and art under one programme, with no gaps. Speak to Taurus.

    FCA Regulated Broker

    Independent High-Value Home Insurance Advice

    We compare specialist private client insurers, present your homes and collection properly and explain the differences between wordings in plain English.

    • Specialist private client insurer comparison
    • Homes, contents and valuables considered together
    • Policy wording and valuation support
    Get a Quote

    A response within 24 working hours, no obligation

    Related Specialisms

    Explore the specialist cover most relevant to this guide.

    high-value home insurance

    Pairs and sets cover explained: what you are paid when one earring, chair or vase is lost, and how better wordings protect the set. Talk to Taurus.

    View high-value home insurance

    heritage property insurance

    Cover for historic homes and traditionally constructed properties.

    View heritage property insurance

    residential property insurance

    Cover for let homes and residential property holdings.

    View residential property insurance
    CallGet a Quick Quote
    32 Reviews
    REVIEWS.io
    5 Rating
    32 Reviews
    Shannon
    Verified Customer
    Billy was very helpful in helping me arrange my insurance. He was prompt when replying to emails, knowledgeable and friendly. Thank you Taurus Risk Management!
    Edward
    Verified Customer
    V. responsive and helpful in pulling together and agreeing a quote for buildings insuruance. Would recommend
    Jack
    Verified Customer
    We engaged Taurus Risk to advise on and place cover for a large residential building in North London. Thomas in particular was fantastic, provided timely and well thought out advice, and more importantly advised us appropriately for the risk we needed to cover. We ended up moving from our previous broker as the service and options for cover was far better than what our previous broker was offering. I stand behind and would definitely recommend Taurus Risk.
    Robert
    Verified Customer
    Chris was brilliant - he really helped us out to find a competitive quote when we were having trouble with other brokers. He turned a quote around in record time and was diligent and helpful. We will definitely be using Taurus again next year.
    Beverley
    Verified Customer
    Our needs were assessed and understood. We received a timeous and properly considered solution in a very short space of time. An absolute pleasure.
    Camilla
    Verified Customer
    Chris was a pleasure to deal with. He was very responsive, provided an excellent service and was professional. I would recommend Taurus who are reliable and efficient, and get you the best deal.
    Raj
    Verified Customer
    Very professional took time to listen and set my cover accordingly pleaseure to deal with. Thank you!
    Imran
    Verified Customer
    I found Taurus online last year and this is my second year I am using Taurus for my Insurance renewal. Chris and Billy have both been very good to me and our relationship is not just about me asking for a insurance policy but we have a general chat which makes a huge difference when deciding should I shop around or actually Taurus take care of me so why should I have to look elsewhere. The pricing is competitive and I receive good advice. I am happy I have found an excellent organisation
    Sairah
    Verified Customer
    Had a very competitive quote from Chris Foster - multi property, including rent cover. Gone ahead with the policy, and hope the underwriters will be a good solution, should anything occur.
    Jonathon
    Verified Customer
    Tom and Billy of Taurus Risk Management provide a highly personalised and commercially focused service. They take the time to ensure that clients fully understand their insurance policies and that cover arrangements are aligned with their specific requirements. Their approach is centred on understanding each client's budget, objectives, and any operational constraints, enabling them to source the most suitable and competitive insurance solutions available. Combined with their professional, approachable, and responsive manner, they instil confidence throughout the process and make it clear that you are working with a trusted and knowledgeable team. I would have no hesitation in recommending Taurus Risk Management to individuals and businesses seeking expert insurance advice and exceptional client service.
    Suzie
    Verified Customer
    Quick and easy process, Chris was very helpful in ensuring we get the right cover for a reasonable price. Would highly recommend.
    Clare
    Verified Customer
    Chris helped me secure buildings insurance for a group of 6 residential buildings - a mix HMO and flats, he obtained several quotes for me to consider and the price was very competitive. The service was brilliant and I would definitely use Taurus risk management again.
    Alexandra
    Verified Customer
    I recently purchased house and travel insurance through Taurus Risk and had an excellent experience. From the initial communication to their prompt and efficient responses, the team demonstrated a high level of professionalism throughout. They addressed all of my questions quickly and provided clear, valuable advice. I would highly recommend Taurus Risk to anyone seeking a reliable and knowledgeable insurance broker.
    Warren
    Verified Customer
    It was an absolute pleasure working with Taurus. From the beginning it felt like the team had a genuine interest in my priorities and what was most important. Looking forward to our partnership together.
    Meg
    Verified Customer
    Team Taurus did a great job - providing fantastic client service. We are very happy with our insurance coverage.