PageID: insights-thatched-property-insurance

    We use cookies to analyse traffic and personalise content. Privacy Policy

    We use cookies

    GDPR Compliant

    We use cookies and similar technologies to enhance your browsing experience, analyse website traffic, and provide personalised content. By clicking "Accept All", you consent to our use of cookies. Learn more in our Privacy Policy

    Back to Insights
    Listed & Heritage Buildings
    listed building insurance
    high-value home insurance

    Thatched Property Insurance: What Insurers Look For

    Thatched property insurance is buildings and contents cover for a home with a thatched roof. It is not hard to arrange, but insurers look closely at fire risk: chimneys, wood burners, wiring and fire barriers. Good maintenance, clear records and an accurate rebuild cost make the biggest difference to the terms you are offered.

    This guidance applies whether or not your thatched property is listed. See our listed and heritage building insurance page for how we approach thatched and other traditionally built homes.

    By Taurus Risk · Published

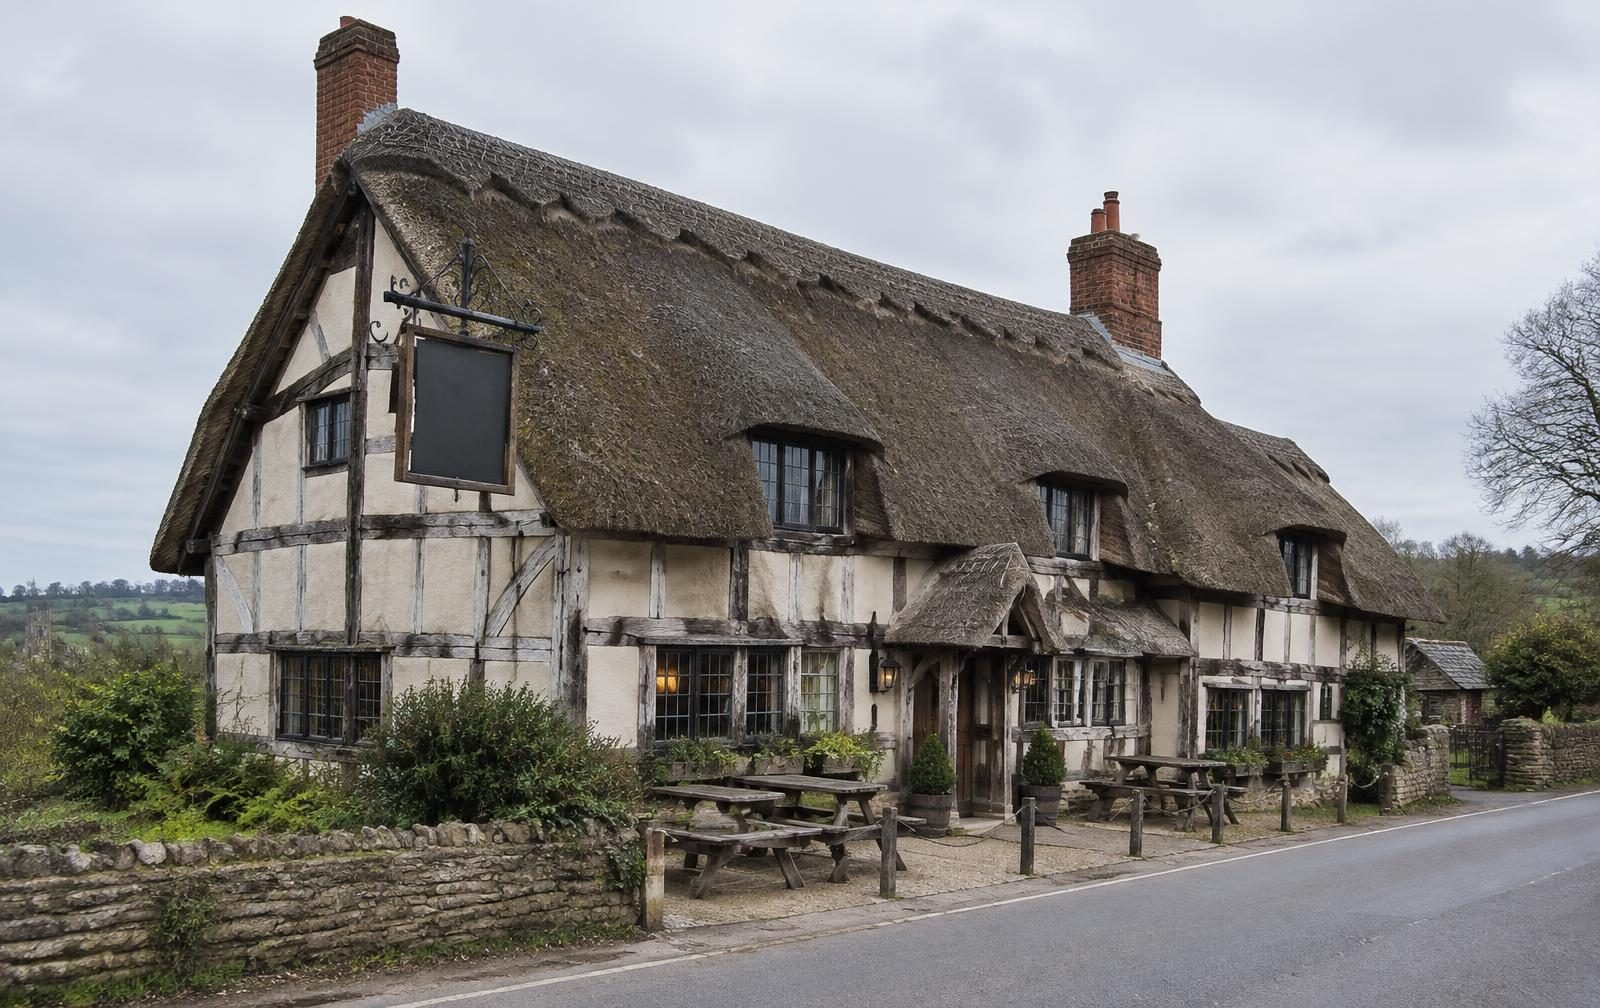
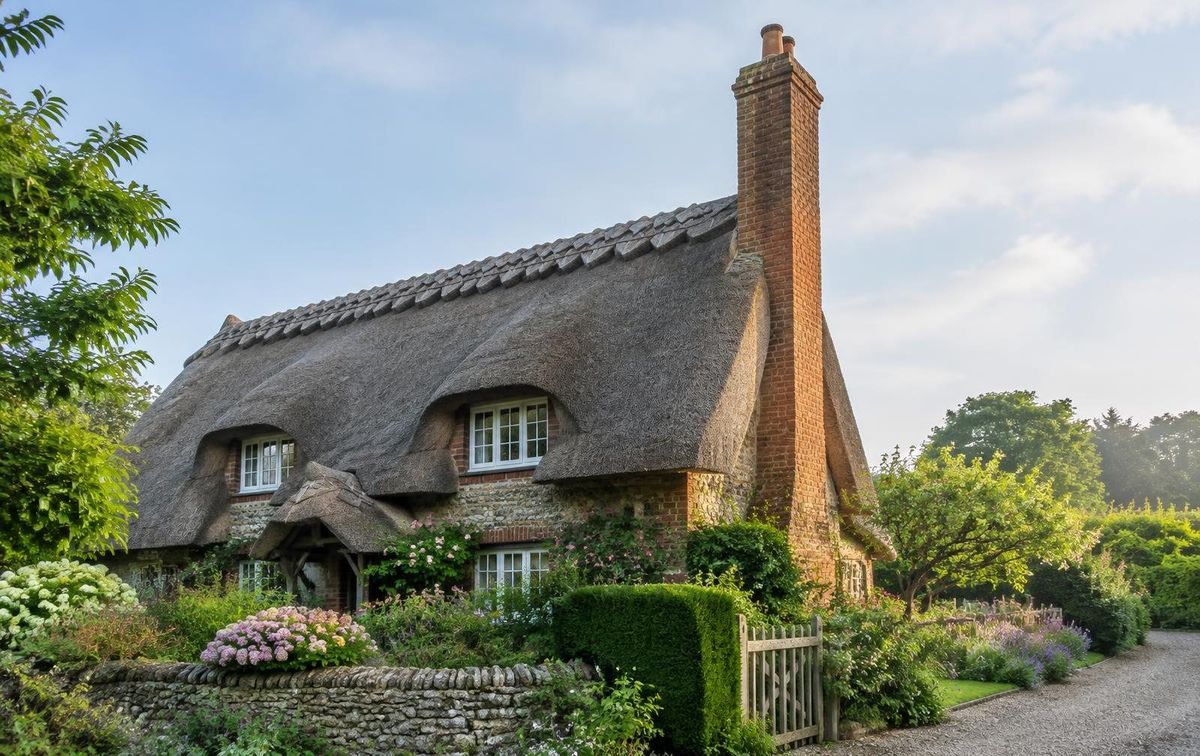
    Thatched cottage with a tall chimney above the ridge, illustrating thatched property insurance

    Is it difficult to insure a thatched house?

    No, but it is a specialist risk and not every insurer will quote. Those that do ask more questions than for a tiled roof, mainly about fire.

    Thatching Advisory Services, a thatch fire-safety specialist, says there are 60,000 thatched properties in the UK, and that 50 to 80 suffer a serious fire each year. It also says the incidence of fire in thatched properties "is no higher than any other type of roofing materials". The concern for insurers is severity: a thatch fire is hard to put out and can destroy the whole roof.

    That is why insurers focus on how ignition is prevented and how quickly a fire would be detected. A well-presented risk usually finds a market.

    What do insurers ask about a thatched property?

    Insurers typically ask about the thatch itself, heat sources, the electrics and fire protection. Expect questions like these:

    AreaTypical insurer questionsGood practice from thatch fire-safety guidance
    ThatchWhat material? When was it last rethatched and re-ridged? Who did the work?Keep invoices and the thatcher's details
    ChimneysHow many? Height above the ridge? When last swept?Chimney at least 1.8m above the ridge; swept at least once a year
    Wood burners and open firesType of appliance? Is the flue lined, and with what?Suitably lined flue; well-seasoned wood with moisture content of no more than 20%
    Spark arrestorsIs one fitted?Not recommended, as the mesh can block; if fitted, clean regularly
    ElectricsWhen was the wiring last inspected? Any cables or lights in the roof space?Inspection every five years; enclosed wiring; bulkhead fittings in the loft
    Fire protectionIs there a fire barrier or retardant? Smoke and heat detection?Barriers and retardants can reduce risk; some insurers offer a discount
    Rebuild costWhat is the sum insured and how was it calculated?Professional reinstatement valuation

    Why are chimneys and wood burners the main concern?

    Because most serious thatch fires are linked to heating. Thatching Advisory Services reports that 90% of homes affected by thatch fires had a wood-burning stove with either a flexible chimney liner or no liner at all.

    Its guidance for chimneys and stoves includes:

    • the chimney, including the pot, should end at least 1.8m above the ridge, citing Building Regulations Approved Document J;
    • chimneys should be professionally swept at least once a year, and more often with regular use;
    • consider an annual camera survey of the flue;
    • burn well-seasoned or kiln-dried wood with a moisture content of no more than 20%;
    • do not light fires with flammable liquids, paper or cardboard;
    • put the fire out before going to bed or leaving the house.

    Raising a chimney will normally need planning permission, and listed building consent if the property is listed. Keep sweep certificates, as insurers may ask for evidence.

    Should I fit a spark arrestor?

    Thatching Advisory Services does not recommend fitting spark arrestors, because the mesh can block with soot and tar. If one is already fitted, it should be cleaned regularly.

    Insurer requirements can differ, so check your policy wording before removing or fitting one.

    Do electrics matter for thatched roof insurance?

    Yes. Electrical faults are a fire risk in any home, and in a thatched roof space the consequences are worse.

    Thatching Advisory Services recommends having circuits inspected every five years by a qualified electrician. It notes that insurers' required intervals range from five to ten years, so check your policy. Wiring in the loft should be enclosed in trunking or conduit, and all cables, including aerial cables, kept away from the thatch.

    Loft lights should be enclosed bulkhead fittings, positioned away from the thatch where possible. Smoke and heat detectors, and a carbon monoxide detector where there is a stove, add protection.

    Do fire barriers and retardants reduce premiums?

    They can. According to Thatching Advisory Services, some insurers offer a discount where a fire retardant or fire barrier is fitted.

    Fire barriers are boards or membranes fitted beneath the thatch, usually when the roof is rethatched. Retardants are treatments applied to the thatch. Ask your insurer before investing, so you know whether and how it will be recognised.

    How long does thatch last?

    It depends on the material, roof pitch, exposure and the quality of the work. Thatching Advisory Services gives these approximate life expectancies under normal conditions:

    MaterialApproximate lifespanRidge replacement
    Water reedUp to about 50 yearsEvery 10 to 15 years
    Combed wheat reed20 to 30 yearsEvery 10 to 15 years
    Long straw15 to 25 yearsEvery 10 to 15 years

    Lifespans can be shorter in humid areas such as the West Country, or under overhanging trees. Insurers are not interested in age for its own sake. They want to know the roof is maintained, weathertight and free of moss build-up and damage, and records of timely re-ridging help show that.

    How do you work out the rebuild cost of a thatched home?

    The rebuild cost is what it would cost to rebuild the property with the same materials and methods after a total loss. It is not the market value.

    Thatch adds cost in materials and skilled labour. If the home is also listed, reinstatement is required to be like for like with matching materials. Online calculators rarely reflect this. Our guide to listed building rebuild cost explains how valuations are prepared.

    Illustrative example: a three-bedroom thatched cottage has a market value of £700,000. A reinstatement valuation allowing for cob walls, water reed thatch and listed building requirements could produce a different, and possibly higher, figure. The sum insured should follow the valuation, not the sale price.

    What if my thatched home is also high value?

    Many thatched homes hold valuable contents as well as historic fabric. A high net worth home insurance policy can combine buildings, contents, art and jewellery cover in one place. See our guide to high-value home insurance and our private client insurance page.

    What to have ready for a quote

    • The thatch material, the date of the last rethatch and re-ridge, and the thatcher's details.
    • Whether the property is listed, and its grade or category.
    • Construction of the walls, roof structure and floors, and the age of each part.
    • A current rebuild valuation: its figure, when it was done and by whom.
    • The number of chimneys, their height above the ridge and recent sweep certificates.
    • Details of any stove or open fire, and the type of flue liner.
    • Whether an electrical inspection has been carried out, and when, including wiring in the roof space.
    • Any fire barrier, retardant, smoke, heat or carbon monoxide detection.
    • Intruder alarm and other security.
    • How the property is occupied and used, including any letting or business use.
    • Any periods the property is, or will be, unoccupied.
    • Any planned or ongoing works, including rethatching.
    • Your claims record for the last five years.
    Frequently asked questions

    How Taurus can help

    We compare insurers with appetite for thatched, listed and heritage homes and a strong record of handling large heritage claims. We present your home with the detail they need: thatch history, chimney and stove records, when the wiring was last inspected and an accurate rebuild cost. We then explain any conditions in plain English.

    Read more about our listed and heritage building insurance service. To talk through your property, call 020 3958 2070, email Enquiries@Taurus-Risk.com or request a quote. We aim to give you a response within 24 working hours.

    Get a listed and heritage quote

    This guide provides general information, not individual insurance or legal advice. Cover is subject to policy terms, conditions and exclusions.

    Related guides

    Listed building rebuild costListed building renovation insuranceInsuring a Listed Building: The Complete UK Guide (2026)
    Related Insights

    Listed & Heritage Building Insurance Industry Insights

    Stay informed with our latest insights, guides, and expert analysis specifically relevant to the listed & heritage building insurance sector.

    Insuring a Listed Building: The Complete UK Guide (2026)
    Listed & Heritage Buildings

    Insuring a Listed Building: The Complete UK Guide (2026)

    Insuring a listed building? Learn how like-for-like rebuild, consent and heritage claims work, how to avoid underinsurance, and how a broker can help.

    Listed Hotel Insurance: What Owners and Operators Need to Know
    Listed & Heritage Buildings

    Listed Hotel Insurance: What Owners and Operators Need to Know

    Listed hotel insurance explained: heritage rebuild values, longer business interruption, fire risk and who insures what. Speak to a Taurus broker today.

    Listed Pub Insurance: Covering Historic Inns and Free Houses
    Listed & Heritage Buildings

    Listed Pub Insurance: Covering Historic Inns and Free Houses

    Listed pub insurance explained: thatched and timber-framed inns, rebuild cost vs sale value, business interruption and leases. Get broker advice today.

    Listed Commercial Building Insurance: Offices, Shops and Mixed-Use
    Listed & Heritage Buildings

    Listed Commercial Building Insurance: Offices, Shops and Mixed-Use

    Listed commercial building insurance for landlords: FRI leases, flats above shops, loss of rent, liability and empty units. Speak to a Taurus broker.

    Listed Building Rebuild Costs: Why Your Sum Insured Is Probably Wrong
    Listed & Heritage Buildings

    Listed Building Rebuild Costs: Why Your Sum Insured Is Probably Wrong

    Rebuild cost for a listed building is rarely market value. See what a reinstatement cost assessment includes, avoid underinsurance and ask a broker.

    Underinsurance on Listed and Heritage Buildings
    Listed & Heritage Buildings

    Underinsurance on Listed and Heritage Buildings

    Underinsurance on a listed building lets the average clause cut every claim. See why it happens, how to fix it and get your sum insured checked.

    FCA Regulated Broker

    Independent Listed Building Insurance Advice

    We compare insurers with appetite for listed and heritage buildings and a strong record of handling large heritage claims.

    • Specialist heritage insurer comparison
    • Reinstatement values and policy bases explained
    • Support with heritage claims
    Get a Quote

    A response within 24 working hours, no obligation

    Related Specialisms

    Explore the specialist cover most relevant to this guide.

    listed building insurance

    Thatched property insurance explained: the fire risks insurers assess, chimneys, wiring, fire barriers and rebuild cost. Speak to a specialist broker.

    View listed building insurance

    high-value home insurance

    Thatched property insurance explained: the fire risks insurers assess, chimneys, wiring, fire barriers and rebuild cost. Speak to a specialist broker.

    View high-value home insurance

    residential property insurance

    Cover for let homes and residential property holdings.

    View residential property insurance
    CallGet a Quick Quote
    32 Reviews
    REVIEWS.io
    5 Rating
    32 Reviews
    Shannon
    Verified Customer
    Billy was very helpful in helping me arrange my insurance. He was prompt when replying to emails, knowledgeable and friendly. Thank you Taurus Risk Management!
    Edward
    Verified Customer
    V. responsive and helpful in pulling together and agreeing a quote for buildings insuruance. Would recommend
    Jack
    Verified Customer
    We engaged Taurus Risk to advise on and place cover for a large residential building in North London. Thomas in particular was fantastic, provided timely and well thought out advice, and more importantly advised us appropriately for the risk we needed to cover. We ended up moving from our previous broker as the service and options for cover was far better than what our previous broker was offering. I stand behind and would definitely recommend Taurus Risk.
    Robert
    Verified Customer
    Chris was brilliant - he really helped us out to find a competitive quote when we were having trouble with other brokers. He turned a quote around in record time and was diligent and helpful. We will definitely be using Taurus again next year.
    Beverley
    Verified Customer
    Our needs were assessed and understood. We received a timeous and properly considered solution in a very short space of time. An absolute pleasure.
    Camilla
    Verified Customer
    Chris was a pleasure to deal with. He was very responsive, provided an excellent service and was professional. I would recommend Taurus who are reliable and efficient, and get you the best deal.
    Raj
    Verified Customer
    Very professional took time to listen and set my cover accordingly pleaseure to deal with. Thank you!
    Imran
    Verified Customer
    I found Taurus online last year and this is my second year I am using Taurus for my Insurance renewal. Chris and Billy have both been very good to me and our relationship is not just about me asking for a insurance policy but we have a general chat which makes a huge difference when deciding should I shop around or actually Taurus take care of me so why should I have to look elsewhere. The pricing is competitive and I receive good advice. I am happy I have found an excellent organisation
    Sairah
    Verified Customer
    Had a very competitive quote from Chris Foster - multi property, including rent cover. Gone ahead with the policy, and hope the underwriters will be a good solution, should anything occur.
    Jonathon
    Verified Customer
    Tom and Billy of Taurus Risk Management provide a highly personalised and commercially focused service. They take the time to ensure that clients fully understand their insurance policies and that cover arrangements are aligned with their specific requirements. Their approach is centred on understanding each client's budget, objectives, and any operational constraints, enabling them to source the most suitable and competitive insurance solutions available. Combined with their professional, approachable, and responsive manner, they instil confidence throughout the process and make it clear that you are working with a trusted and knowledgeable team. I would have no hesitation in recommending Taurus Risk Management to individuals and businesses seeking expert insurance advice and exceptional client service.
    Suzie
    Verified Customer
    Quick and easy process, Chris was very helpful in ensuring we get the right cover for a reasonable price. Would highly recommend.
    Clare
    Verified Customer
    Chris helped me secure buildings insurance for a group of 6 residential buildings - a mix HMO and flats, he obtained several quotes for me to consider and the price was very competitive. The service was brilliant and I would definitely use Taurus risk management again.
    Alexandra
    Verified Customer
    I recently purchased house and travel insurance through Taurus Risk and had an excellent experience. From the initial communication to their prompt and efficient responses, the team demonstrated a high level of professionalism throughout. They addressed all of my questions quickly and provided clear, valuable advice. I would highly recommend Taurus Risk to anyone seeking a reliable and knowledgeable insurance broker.
    Warren
    Verified Customer
    It was an absolute pleasure working with Taurus. From the beginning it felt like the team had a genuine interest in my priorities and what was most important. Looking forward to our partnership together.
    Meg
    Verified Customer
    Team Taurus did a great job - providing fantastic client service. We are very happy with our insurance coverage.