When is a listed building treated as unoccupied?
Insurers generally treat a building as unoccupied when no one has lived in it, or used it normally, for a continuous period set out in the policy. The period and wording vary between insurers, so read your own policy schedule.
Some policies set the period at only a few weeks, so tell your insurer or broker as soon as you know a property will be empty. Some policies also treat a building as unoccupied if it is only partly used, or used only for storage. Our wider guide to unoccupied property insurance in 2026 covers the general market in more detail.
Common reasons a listed building falls empty include:
- probate, after an owner dies;
- a sale or purchase that takes time to complete;
- major renovation (see our guide to listed building renovation insurance);
- a commercial tenant leaving, such as a pub or hotel between operators;
- the owner moving abroad or into care.
If a let building falls empty, rental income can stop too. Our guide to loss of rent insurance explains how that cover works.
What does unoccupied insurance usually cover?
Cover for empty buildings is often narrower than for occupied ones. Insurers commonly restrict escape of water, theft, malicious damage and accidental damage once a building is unoccupied.
Some insurers will reinstate wider cover if you meet stricter conditions. Others offer only fire, lightning, explosion and aircraft cover for long-term empty buildings. The right answer depends on the building, its location and how long it will be empty.
| Area | What insurers commonly look for | Why it matters for a listed building |
|---|---|---|
| Inspections | Regular recorded visits, often weekly, inside and out | Early detection of leaks, break-ins and roof damage before historic fabric is lost |
| Water and heating | Water drained down and supply turned off, or heating kept on at a minimum temperature | Burst pipes can ruin lime plaster, panelling and decorative ceilings |
| Security | All doors and windows secured, keys controlled, alarm maintained | Fireplaces, panelling and architectural salvage attract thieves |
| Combustibles | Waste, furniture and packaging removed | Reduces fuel for arson |
| Letterboxes | Sealed, or fitted with a metal box emptied regularly | Reduces the risk of fire set through the letterbox |
| Changes | Insurer told of any change in occupancy, sale or works | Undisclosed changes can affect claims |
How often should an empty listed or heritage building be inspected?
Many insurers expect at least weekly inspections, with each visit recorded. You can carry them out yourself or appoint someone to act for you.
Inspections should cover the inside and outside of the building. Record the date, who visited and what was found, and fix any defects quickly. If you cannot visit yourself, a local agent, caretaker or property manager can do it.
A good inspection checklist includes:
- roofs, gutters and rainwater goods, including lead flashings;
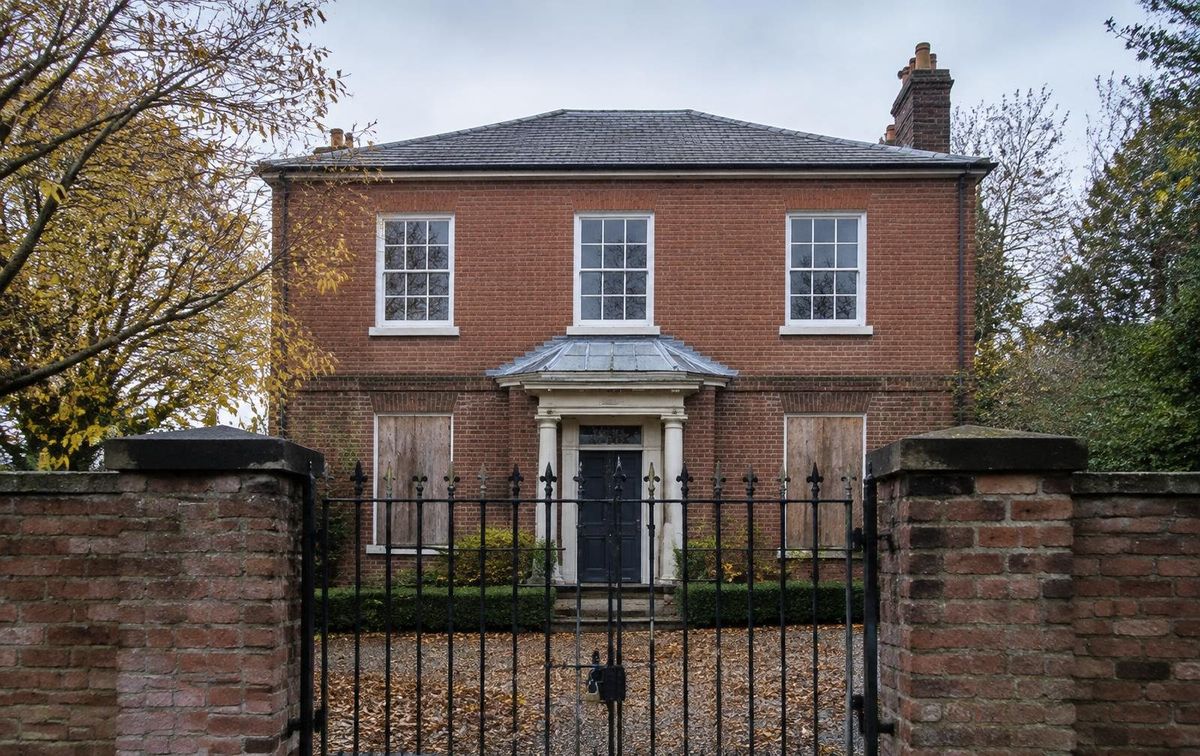
- doors, windows, locks and boarding;
- signs of entry, squatting or rough sleeping;
- water staining, damp or leaks inside;
- post and free newspapers removed;
- rubbish or fly-tipping in the grounds.
What are the main risks to an empty listed or heritage building?
The main risks are arson, vandalism, theft of metals and architectural features, and escape of water. Each can cause damage that is slow and expensive to put right on a listed or heritage building.
Arson and vandalism
Empty buildings attract vandals and arsonists. Reduce the risk by removing combustible items, moving skips and bins away from the building, and keeping the property maintained so it does not look abandoned.
Visible security helps. Alarms, security lighting, CCTV and wireless sensors are all options, depending on the building and the insurer's requirements.
Lead and metal theft
Lead roofs, copper and other metals are a target, and an empty building gives thieves time. Once lead is stripped, rain gets in quickly and can damage timbers and interiors.
Ask your insurer whether a metal theft limit applies, and what security they want to see. Roof alarms, anti-climb measures and marking systems are options to discuss with a security specialist.
Escape of water
A slow leak in an empty building can go unnoticed for weeks, and the damage grows the longer it runs.
Insurers commonly ask for the water supply to be turned off and the system drained, or for heating to be maintained. Which they prefer depends on the building, so confirm it in writing.
What is the Heritage at Risk Register?
The Heritage at Risk Register is Historic England's record of historic sites in England considered at risk. Buildings are assessed on the basis of condition and occupancy or use.
The buildings and structures part of the register includes Grade I and II* listed buildings, Grade II listed places of worship, and Grade II listed buildings in London. Secular Grade II buildings outside London are not included. Historic England updates the register regularly, and its 2025 edition is the latest referenced on its website at the time of writing.
Being on the register is not an insurance condition in itself. But a building that is empty and deteriorating needs careful presentation to insurers, and its condition will be scrutinised.
What are an owner's legal duties for an empty listed building?
Owners remain responsible for an empty listed building. If it is allowed to deteriorate, the local authority can step in. In England, section 54 of the Planning (Listed Buildings and Conservation Areas) Act 1990 lets it carry out works urgently necessary for the building's preservation.
These works may include temporary support or shelter. The authority is required to give the owner at least seven days' written notice before works begin. Under section 55, the authority can then recover the cost from the owner, who has 28 days to make representations against the notice.
Unauthorised works to an empty listed building, such as stripping out features, are a criminal offence under the same Act. The rules differ in Scotland and Wales, so check with your local authority.
What does a well-managed vacancy look like?
Illustrative example: an owner inherits a Grade II house. Probate will take six months and the house will be sold afterwards.
The owner tells the insurer in the first week, agrees to weekly recorded inspections, drains down the water system and installs a monitored alarm. The insurer continues cover on agreed terms, and the owner has a clear record of every visit if a claim arises.
Checklist: what to tell your insurer when a building falls empty
- The date the building became, or will become, empty and how long you expect it to stay empty.
- The reason, such as probate, sale, renovation, closure of a business or a tenant leaving.
- The listing grade or category.
- Construction of the walls, roof, floors and framing, and the age of each part.
- The current rebuild valuation (when and by whom), which should still reflect like-for-like reinstatement.
- Whether an electrical inspection has been carried out, and when, and whether the supply will be isolated.
- Whether water will be drained down or heating kept on.
- Alarm, lighting, locks and any boarding or roof protection.
- Who will inspect the building, how often, and how visits will be recorded.
- How each part was used before it became empty, and any parts still occupied.
- Any planned works, sale or change of use.
- Your claims record for the last five years.
- If a business traded from the building: when it stopped trading and any rent or income still due.
If you are unsure the valuation is right, see our guide to listed building rebuild cost.