Do I need to tell my insurer about building works?
Yes, in almost every case. Most property policies treat significant works as a material change in risk, and some restrict cover during works unless the insurer has agreed them.
Talk to your broker as soon as building work is planned. Telling the insurer late, or only after a loss, is where problems usually start.
When you notify the insurer, expect questions about:
- the scope of works and the contract value;
- the expected start and finish dates;
- whether you will live in the property during the works;
- whether any hot works (welding, torches, lead work, paint stripping with heat) are planned;
- who the contractor is and what insurance they carry.
The insurer may continue cover as normal, add conditions, or ask for more detail. If your home is high value or part of a wider portfolio, our private client insurance team can coordinate this with your other policies.
Who insures the existing building and who insures the works?
Your own property insurer normally covers the existing building. The new works are often insured by the contractor or under a joint names policy, depending on what the building contract says.
The distinction matters because a fire can damage both at once. If the contract and the policies do not line up, there is a risk of a gap or a dispute between insurers.
| Risk | Typical insurer | What to check |
|---|---|---|
| Existing structure and its contents | Owner's property insurer | Insurer told about works; any conditions accepted; sum insured still reflects like-for-like rebuild |
| New works and unfixed materials on site | Contractor's contract works insurer, or a joint names policy | Who the contract says insures the works, and for what amount |
| Injury to the public or damage to neighbours caused by the contractor | Contractor's public liability insurer | Limit of indemnity and that the policy is in force |
| Injury to the contractor's employees | Contractor's employers' liability insurer | Certificate showing at least the legal minimum |
| Your own liability as owner | Owner's property owner's or household liability cover | That cover continues during the works |
How do JCT contracts deal with insurance?
Many UK projects use contracts published by the Joint Contracts Tribunal (JCT). Their insurance provisions deal with physical damage to the works, site materials and, where relevant, existing structures.
The wording differs between JCT contracts and editions, and the right option depends on your project. Ask your architect or contract administrator which insurance option has been selected before you sign. Then send that wording to your broker.
What is a joint names policy?
A joint names policy is a single policy that names both the owner and the contractor as insured. On renovation and extension projects it is often used so that one policy can respond to the existing structure and the works.
Because both parties can claim under the same policy, there is less scope for arguments over who pays. If your contract calls for joint names cover, tell your own property insurer, because it affects how their policy works alongside the contractor's.
Do I need listed building consent before renovating?
Yes, if the works would affect the building's character as a building of special architectural or historic interest. In England, section 7 of the Planning (Listed Buildings and Conservation Areas) Act 1990 prohibits such works unless they are authorised.
Historic England is clear that "carrying out works to a listed building without listed building consent is a criminal offence". Listing covers the whole building, so internal alterations and window replacements can need consent. Planning permission may be needed as well.
Under section 9 of the Act, the maximum penalty on summary conviction is six months' imprisonment, a fine, or both. On conviction on indictment it is up to two years' imprisonment, a fine, or both. Failing to comply with a condition attached to a consent is also an offence.
Listed building consent does not apply to unlisted heritage buildings, although planning rules can still apply in conservation areas. The rules differ in Scotland and Wales, so check with your local authority.
How can unauthorised works affect insurance?
Unauthorised works can affect a claim in several ways. The insurer may argue that the risk changed without being disclosed, and any reinstatement is still subject to the conservation officer's approval.
If original fabric has been removed without consent, the local authority may require it to be put back. Most property policies are not designed to pay for putting unauthorised work right. Keep consents, approved drawings and conditions on file with your insurance papers.
The biggest risks when renovating listed and heritage buildings
Fire is the most serious risk to a listed or heritage building during works. Escape of water, theft and accidental damage follow close behind.
Hot works and fire
Hot works are any work that uses a naked flame or generates heat, such as lead welding, soldering and heat guns. Historic roofs and voids contain dry timber, old debris and hidden routes for fire to spread.
Insurers commonly require a hot work permit where hot works are involved. The permit system makes sure fire precautions are taken before, during and after the work. Ask your contractor how they control hot works and whether cold alternatives exist.
Simple site disciplines help:
- remove combustible waste daily and keep skips away from the building;
- confirm workers know where extinguishers and emergency telephones are;
- check the building at the end of each day, and periodically during it.
Security and scaffolding
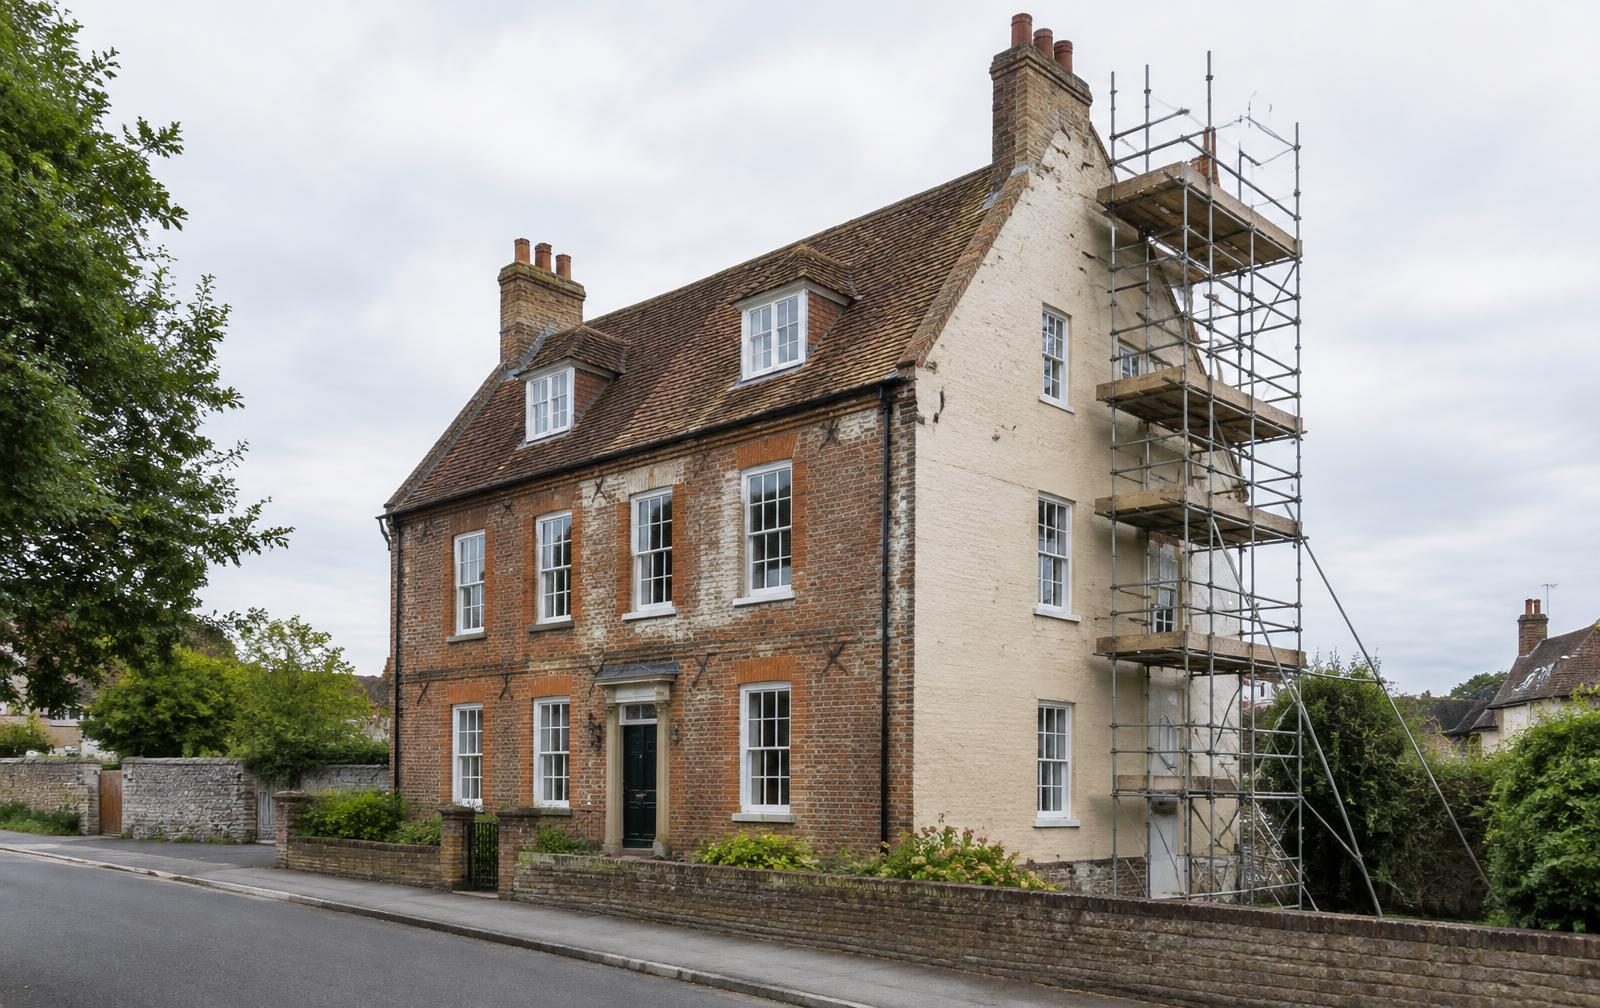
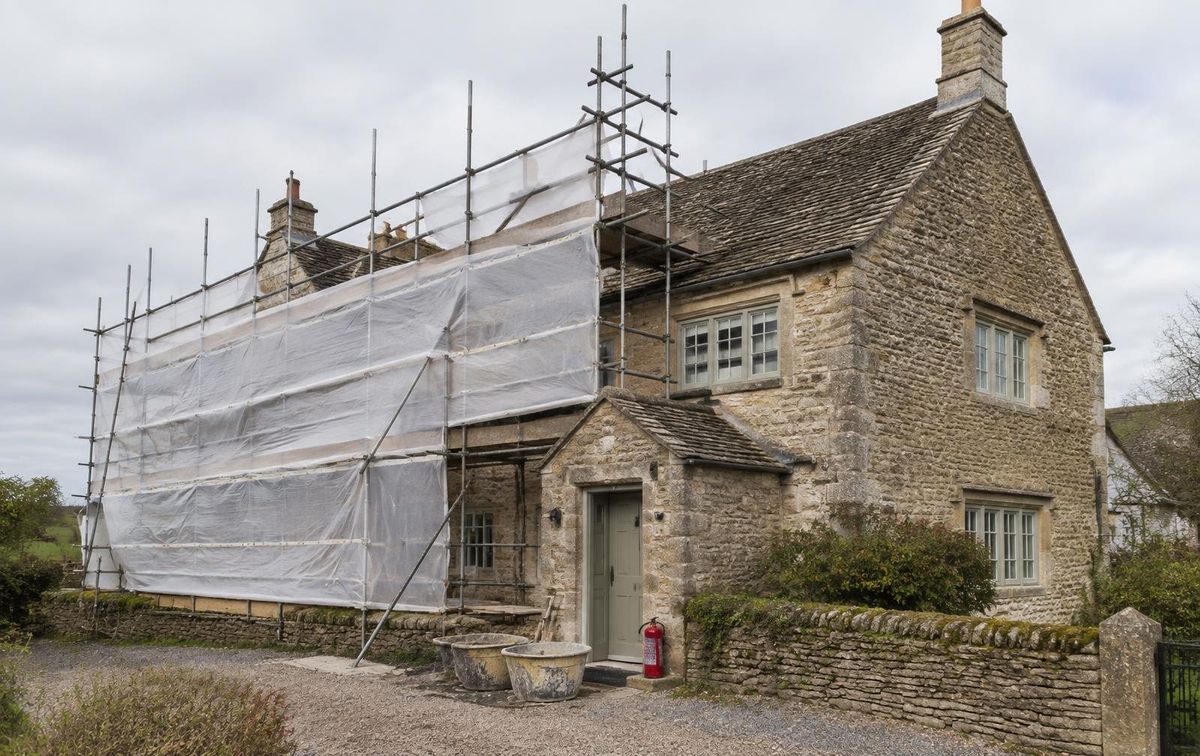
Scaffolding gives easy access to upper floors and roofs. Lead, copper and tools on site attract thieves.
Ask the contractor to secure ladders out of hours and consider scaffold alarms. It is also sensible to tell the local police and fire service before major works start.
Unoccupancy during works
Many owners move out while major works are carried out. Most property policies have an unoccupancy clause that restricts cover after a set period. A house full of contractors by day and empty at night may count as unoccupied.
Tell your insurer if you will not be living there. Our guide to empty listed building insurance explains the conditions insurers commonly apply.
What insurance should my contractor have?
At a minimum, a contractor should hold public liability insurance and, if they have employees, employers' liability insurance. GOV.UK says employers' liability is legally required to cover at least £5 million, and employers can be fined £2,500 for every day they are not properly insured.
Ask to see the certificates, not just a statement that cover exists. Check:
- the insured name matches the business you are contracting with;
- the policy dates cover the whole project;
- the public liability limit is adequate for damage to your building and neighbouring property;
- whether the contractor holds contract works or all-risks cover, if the contract requires them to insure the works;
- whether any designer on the project, such as an architect or structural engineer, holds professional indemnity insurance.
Ask for a method statement and risk assessment too. For a listed or heritage building, ask about the contractor's experience with lime, timber frame or the relevant traditional techniques.
Does renovation change my sum insured?
Often, yes. Improvements can increase the cost of reinstating the building like for like, so your sum insured should reflect the finished building.
Illustrative example: an owner with a £1,500,000 rebuild valuation adds a new oak-framed extension and restores a lime-plaster ceiling. Once complete, the rebuild cost may be materially higher. If the sum insured is not updated, a later claim could be reduced for underinsurance.
Our guide to listed building rebuild cost explains how valuations are prepared.
Checklist: what to have ready before works start
- A description of the works, the contract value and the expected start and finish dates.
- The building contract, including the insurance option selected.
- Copies of the contractor's public liability and employers' liability certificates.
- Listed building consent, approved drawings and any conditions, where consent is needed.
- How hot works, site security and waste will be managed.
- Whether you will live in the property during the works, and any periods it will be empty.
- The listing grade or category.
- Construction of the walls, roof, floors and framing, and the age of each part.
- Your current rebuild valuation (when and by whom), adjusted for the works, and your policy schedule.
- Whether an electrical inspection has been carried out, and when, and any rewiring planned.
- Heating, fire and security protections, including any temporary measures during the works.
- How each part of the building is used.
- Your claims record for the last five years.